シャドーイング練習: America Is Quietly Drowning in Debt - 動画で英語スピーキングを学ぶ

練習モードを選ぶ

各モードは全画面の練習ルームで開きます。

129 文
文が短すぎたり長すぎる場合は、Editをタップして調整してください。
1
The United States economy.
2
Everything seems to be going great.
3
The stock market's at an all -time high.
4
The Federal Reserve's inflation strategy seems to be working, and Arby's just released steak nuggets.
5
On the surface, life is good but underneath there's trouble brewing, Because while everyone's busy debating the next interest rate cut, or whether Tucker Carlson wears a toupee,
6
There's a credit crisis bubbling that nobody seems to be talking about.
7
And while the United States government is blowing through cash faster than a bachelor party at 2am in Miami.
8
That's not even the real issue.
9
The real issue is that the rest of America is looking at this reckless spending and saying, "Hey, that looks kind of fun." And because of this, the United States now has record high levels of household debt,
10
mortgage debt, auto debt, student loan debt, and credit card debt.
11
Moral of the story: Americans are drowning in debt.
12
And by the end of this video, I'm going to show you that the
13
so -called growth everyone's bragging about is really just fueled by a consumer debt crisis that's been building right under everyone's nose.
14
Let's zoom all the way out first.
15
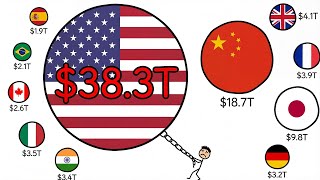
The United States now has more debt than any nation in human history.
16
And the national debt has officially crossed 38 trillion dollars.
17
And borrowing isn't free.
18
We now spend $1 trillion a year just to service the interest on that debt.
19
That means the United States is spending more on interest than we are on national defense, income security programs, and veterans benefits.
20
Interest has become the fastest growing expense in the entire federal budget, rising by over 34 % in just the last two years.
21
Translation?
22
We're shelling out a trillion dollars a year just to keep the lights on and the debt collectors off our front lawn.
23
And here's where it gets worse.
24
The rest of America is following the same playbook.
25
Because if Uncle Sam can max out every car he owns, why shouldn't everyone else?
26
And that's exactly what's happening.
27
The average American now carries over $90 ,000 in personal debt.
28
And total household debt in the United States, which measures debt at a more personal level, has exploded 60 % over the last decade,
29
reaching $18 .6 trillion, the highest level ever recorded.
30
So while the government's piling up debt at the national level, the rest of the country's quietly drowning at the household level.
31
Debt has become the duct tape holding the entire economy together.
32
And have you ever heard of the Clint Eastwood movie, The Good, the Bad, and the Ugly?
33
Well, this same concept can be applied to debt.
34
Because when you actually look closer, not all debt is created equal.
35
There's good debt, there's bad debt, and then there's ugly debt.
36
When you look at how the New York Fed categorizes total household debt in the United States,
37
everything falls into two main buckets: housing debt and non -housing debt.
38
And it's only right to start with the good debt, housing debt.
39
Housing debt is then split even further into two categories: mortgage accounts and home equity revolving accounts.
40
Let's get the main one out of the way first: mortgage accounts.
41
These include every type of long -term home loan, from first mortgages to refinancing to home equity installment loans, They're what the Fed calls closed -end loans,
42
which essentially means you get a chunk of money up front, make monthly payments with interest, and once it's paid off, the accounts close for good.
43
- It's simple English, it's the giant soul -crushing debt you take on for the privilege of owning four walls and a roof.
44
And make no mistake, mortgage balances in the United States are massive.
45
They actually make up the bulk of not just housing debt, but total household debt in America.
46
Total mortgage balances have reached a record $13 trillion, the highest level ever recorded.
47
Now onto the other type of housing debt: home equity revolving accounts.
48
These are also called a home equity line of credit, and are essentially just a credit card for your house.
49
You leverage your home's equity, pay back what you used, and then tell yourself it's an investment since it's technically linked to your house.
50
It was an investment!
51
And while home equity line of credit balances have jumped more than 30 % since 2021, which marks the fastest rise since before the 2008 financial crisis,
52
the overall total remains modest, at roughly $411 billion.
53
So while the overall trend is eyebrow -raising, it's not something that demands immediate concern.
54
So if housing debt is the good older brother in the family, then that raises the question: what's on the other side of things?
55
And that would be non -housing debt.
56
This is the problem child.
57
Non -housing debt is split into four categories: student debt, auto debt, credit card debt, and other.
58
But auto loans in the catch -all other bucket are holding steady for now, so we'll save those for another day.
59
However, the same can't be said for the other two.
60
student loan debt and credit card debt.
61
Next on the list we have student loan debt.
62
America's favorite rite of passage into adulthood and anxiety.
63
And over the past few decades, the cost to go to college has skyrocketed.
64
Why?
65
Because when you combine the ability for 18 year olds to borrow thousands of dollars with no credit history, no collateral, and no financial literacy,
66
you get a system where colleges can charge whatever price they want.
67
And they do.
68
Since 1983, college tuition has skyrocketed more than 700%, which far outpaces inflation, housing costs, and wages.
69
It's the same cycle over and over.
70
Every year universities raise tuition, students take on more loans, and student debt grows.
71
And because of this, there's now $1 .7 trillion in total student loan balances, which marks the highest level recorded in history.
72
Student loan debt now represents roughly 9 % of all household debt in America.
73
And about 44 million Americans still owe money on their education, with an average amount owed of $37 ,000.
74
And this isn't even what's scary.
75
Data is starting to show delinquencies on this debt are climbing sharply.
76
A year ago, less than 1 % of borrowers were in serious delinquency, meaning 90 days or more late on what they owed.
77
Now, that number has risen past 9%.
78
And the worst part?
79
Unlike a mortgage or an auto loan that's secured and has collateral attached, with a student loan, you can't just sell your degree when things go bad.
80
And here's a fun fact for you: student debt is one of the few types of debt
81
that typically doesn't get discharged when you file bankruptcy.
82
Student loans are the her -pkies of the finance world.
83
They never really go away.
84
Now to where it gets ugly: credit card debt.
85
And to say it's just ugly would still be a massive understatement.
86
Because it's not just ugly, it's dangerous.
87
Credit card balances in the United States have now crossed one trillion dollars, which is once again the highest level recorded in history.
88
And credit card debt has risen by more than half since 2020.
89
To add some more context, Americans have added more credit card debt in the last four
90
years than they did in the entire decade following the 2008 financial crisis.
91
And we're not just swiping like lunatics.
92
We're also opening accounts like there's no tomorrow.
93
The number of active credit card accounts has risen 20 % from levels seen before the pandemic, and now exceeds 600 million.
94
And with roughly 340 million individuals in the United States, that means the average American is managing several cards, several monthly payments and several financial headaches.
95
And here's where things start to fall apart.
96
Credit card delinquencies are rising fast.
97
The share of credit card accounts in serious delinquency has now climbed above 12%, which marks the highest level since the 2008 financial crisis.
98
And it's not hard to see why.
99
Over the last few years, inflation has soared, housing costs have reached record highs, and wages haven't come close to keeping up.
100
And here's the cherry on top.
101
The average interest rate on credit cards is now more than 21%, once again hovering around the highest level ever recorded.
102
So that means the 12 % of credit card users who are already delinquent aren't just behind.
103
they're likely drowning in compound interest.
104
And just when it seemed like things couldn't get any more chaotic, a new force arrived on the scene.
105
You've probably seen the buttons.
106
Buy now and pay over time with Affirm.
107
Pay in four installments with Klarna
108
and whatever other soft -colored slogans Silicon Valley could dream up to convince individuals
109
that borrowing money is a form of financial empowerment.
110
But here's the truth.
111
This concept is an innovation.
112
It's a marketing makeover and it's credit disguised as convenience.
113
It's a shiny new way to train an entire generation in normalized debt.
114
In fact, a recent study found that 15 % of all Americans use Buy Now Pay later in 2024, with 40 % of them regretting it after realizing the total costs.
115
And even worse, 24 % of these users have made a late payment, which is up from 18 % in 2023.
116
It's the same old credit trap, just this time with a better user interface.
117
So while headlines keep celebrating that consumer spending remains strong, the reality is people are financing their day -to -day survival one installment plan at a time.
118
And when you start to look at the American economy from a debt -first perspective, everything starts to look a whole lot different.
119
It doesn't look like the booming economy everyone's talking about on CNBC.
120
It looks more like a giant game of hot potato where everyone's hoping the music doesn't stop.
121
Every record high stock market headline, every flashy consumer spending report, it's all built on borrowed money.
122
Because the truth is, America isn't saving for the future, it's financing the present.
123
And that's what makes the credit crisis so dangerous.
124
It's not loud, it's not sudden, and it's not dramatic.
125
It's quiet, it's gradual, and it's happening in plain sight.
126
So yeah, everything appears to be fine on the surface.
127
The markets are high, inflation's easing, and unemployment's low.
128
But underneath, the foundation is beginning to crack.
129
Because this is America, a country that's surviving on debt.

アプリをダウンロード

流暢に話すために必要なすべて

AI発音採点文ごとに採点
IPA練習すべての音をマスター
単語学習自分の単語帳を作る
単語ゲーム遊びながら覚える

同じチャンネル

FOR YOU

おすすめ動画

アメリカのデビット危機、その実態とは?

ビデオでは、表面的に好調な米国経済の裏で、政府と家計の双方で膨大な債務が積み上がっている現状が明らかにされています。株価の高騰やインフレ抑制の成果など、見かけの繁栄の下では、「借金が経済を支える粘着テープ」のような危険な構造が隠されているのです。このようなリアルな社会問題をめぐる議論は、英語スピーキング練習に最適な題材です。なぜなら、経済用語や日常的な表現が混在し、自然な語彙や文法の使い方を学べるからです。

実用的な語句とコロケーション

  • drowning in debt:「借金に溺れる」。比喩的な表現で、多額の借金に苦しむ様子を生き生きと表します。
  • service the interest:「利子を支払う」。債務の利息部分を払うことを指し、経済関連の会話でよく使われます。
  • max out:「限度まで使い切る」。クレジットカードやローンの限度額を使い尽くす場合に用いられ、日常会話でも頻出です。
  • duct tape:「粘着テープ」。ここでは比喩的に「一時的な対策」を意味し、物事の脆弱な構造を表すのに便利な表現です。

あなたのシャドーイングチャレンジ

英語シャドーイング(shadow speech)は、IELTS スピーキング対策にも効果的な練習法です。今回の課題は、ビデオの「the rest of America is following the same playbook」から「the highest level ever recorded」までの部分をシャドーイングすることです。スピーカーのイントネーションやリズムに合わせて、1秒遅れで繰り返し発音してみてください。特に「shelling out a trillion dollars」のような強調された表現は、どのように発音されているか注意して観察しましょう。この練習を通して、自然なスピーキングの流れを身につけることができます。

このような現実的な内容を使った shadowspeak 練習は、語彙力だけでなく、ネイティブの思考過程も理解するのに役立ちます。ぜひ今日から始めて、英語スピーキングのスキルを向上させましょう!

この動画の文法

話し手がよく使っている文型を、動画の実際の表現とともに紹介します。

文型動画での表現
現在完了形 have/has + 過去分詞 — 過去の出来事が今も関係しているhas become · has exploded · have you ever heard
受動態 be + 過去分詞 — 誰がするかより、何が起きるかに焦点を当てるis really just fueled · can be applied · is created
関係詞節 who / which + 節 — 人や物について情報を加えるdollars, which is · payment, which is

シャドーイングとは?英語上達に効果的な理由

シャドーイング(Shadowing)は、もともとプロの通訳者養成プログラムで開発された言語学習法で、多言語習得者として知られるDr. Alexander Arguelles によって広く普及されました。方法はシンプルですが非常に効果的:ネイティブスピーカーの英語を聞きながら、1〜2秒の遅延で声に出してすぐに繰り返す——まるで「影(shadow)」のように話者を追いかけます。文法ドリルや受動的なリスニングと異なり、シャドーイングは脳と口の筋肉が同時にリアルタイムで英語を処理・再現することを強制します。研究により、発音精度、抑揚、リズム、連音、リスニング力、そして会話の流暢さが大幅に向上することが確認されています。IELTSスピーキング対策や自然な英語コミュニケーションを目指す方に特におすすめです。

シャドーイングのやり方: ステップ別の完全ガイドを読む →