쉐도잉 연습: America Is Quietly Drowning in Debt - 영상으로 영어 말하기 배우기

연습 모드 선택

각 모드는 전체 화면 연습실로 열립니다.

129 문장
문장이 너무 짧거나 길면 Edit를 눌러 조정하세요.
1
The United States economy.
2
Everything seems to be going great.
3
The stock market's at an all -time high.
4
The Federal Reserve's inflation strategy seems to be working, and Arby's just released steak nuggets.
5
On the surface, life is good but underneath there's trouble brewing, Because while everyone's busy debating the next interest rate cut, or whether Tucker Carlson wears a toupee,
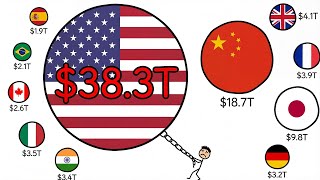
6
There's a credit crisis bubbling that nobody seems to be talking about.
7
And while the United States government is blowing through cash faster than a bachelor party at 2am in Miami.
8
That's not even the real issue.
9
The real issue is that the rest of America is looking at this reckless spending and saying, "Hey, that looks kind of fun." And because of this, the United States now has record high levels of household debt,
10
mortgage debt, auto debt, student loan debt, and credit card debt.
11
Moral of the story: Americans are drowning in debt.
12
And by the end of this video, I'm going to show you that the
13
so -called growth everyone's bragging about is really just fueled by a consumer debt crisis that's been building right under everyone's nose.
14
Let's zoom all the way out first.
15
The United States now has more debt than any nation in human history.
16
And the national debt has officially crossed 38 trillion dollars.
17
And borrowing isn't free.
18
We now spend $1 trillion a year just to service the interest on that debt.
19
That means the United States is spending more on interest than we are on national defense, income security programs, and veterans benefits.
20
Interest has become the fastest growing expense in the entire federal budget, rising by over 34 % in just the last two years.
21
Translation?
22
We're shelling out a trillion dollars a year just to keep the lights on and the debt collectors off our front lawn.
23
And here's where it gets worse.
24
The rest of America is following the same playbook.
25
Because if Uncle Sam can max out every car he owns, why shouldn't everyone else?
26
And that's exactly what's happening.
27
The average American now carries over $90 ,000 in personal debt.
28
And total household debt in the United States, which measures debt at a more personal level, has exploded 60 % over the last decade,
29
reaching $18 .6 trillion, the highest level ever recorded.
30
So while the government's piling up debt at the national level, the rest of the country's quietly drowning at the household level.
31
Debt has become the duct tape holding the entire economy together.
32
And have you ever heard of the Clint Eastwood movie, The Good, the Bad, and the Ugly?
33
Well, this same concept can be applied to debt.
34
Because when you actually look closer, not all debt is created equal.
35
There's good debt, there's bad debt, and then there's ugly debt.
36
When you look at how the New York Fed categorizes total household debt in the United States,
37
everything falls into two main buckets: housing debt and non -housing debt.
38
And it's only right to start with the good debt, housing debt.
39
Housing debt is then split even further into two categories: mortgage accounts and home equity revolving accounts.
40
Let's get the main one out of the way first: mortgage accounts.
41
These include every type of long -term home loan, from first mortgages to refinancing to home equity installment loans, They're what the Fed calls closed -end loans,
42
which essentially means you get a chunk of money up front, make monthly payments with interest, and once it's paid off, the accounts close for good.
43
- It's simple English, it's the giant soul -crushing debt you take on for the privilege of owning four walls and a roof.
44
And make no mistake, mortgage balances in the United States are massive.
45
They actually make up the bulk of not just housing debt, but total household debt in America.
46
Total mortgage balances have reached a record $13 trillion, the highest level ever recorded.
47
Now onto the other type of housing debt: home equity revolving accounts.
48
These are also called a home equity line of credit, and are essentially just a credit card for your house.
49
You leverage your home's equity, pay back what you used, and then tell yourself it's an investment since it's technically linked to your house.
50
It was an investment!
51
And while home equity line of credit balances have jumped more than 30 % since 2021, which marks the fastest rise since before the 2008 financial crisis,
52
the overall total remains modest, at roughly $411 billion.
53
So while the overall trend is eyebrow -raising, it's not something that demands immediate concern.
54
So if housing debt is the good older brother in the family, then that raises the question: what's on the other side of things?
55
And that would be non -housing debt.
56
This is the problem child.
57
Non -housing debt is split into four categories: student debt, auto debt, credit card debt, and other.
58
But auto loans in the catch -all other bucket are holding steady for now, so we'll save those for another day.
59
However, the same can't be said for the other two.
60
student loan debt and credit card debt.
61
Next on the list we have student loan debt.
62
America's favorite rite of passage into adulthood and anxiety.
63
And over the past few decades, the cost to go to college has skyrocketed.
64
Why?
65
Because when you combine the ability for 18 year olds to borrow thousands of dollars with no credit history, no collateral, and no financial literacy,
66
you get a system where colleges can charge whatever price they want.
67
And they do.
68
Since 1983, college tuition has skyrocketed more than 700%, which far outpaces inflation, housing costs, and wages.
69
It's the same cycle over and over.
70
Every year universities raise tuition, students take on more loans, and student debt grows.
71
And because of this, there's now $1 .7 trillion in total student loan balances, which marks the highest level recorded in history.
72
Student loan debt now represents roughly 9 % of all household debt in America.
73
And about 44 million Americans still owe money on their education, with an average amount owed of $37 ,000.
74
And this isn't even what's scary.
75
Data is starting to show delinquencies on this debt are climbing sharply.
76
A year ago, less than 1 % of borrowers were in serious delinquency, meaning 90 days or more late on what they owed.
77
Now, that number has risen past 9%.
78
And the worst part?
79
Unlike a mortgage or an auto loan that's secured and has collateral attached, with a student loan, you can't just sell your degree when things go bad.
80
And here's a fun fact for you: student debt is one of the few types of debt
81
that typically doesn't get discharged when you file bankruptcy.
82
Student loans are the her -pkies of the finance world.
83
They never really go away.
84
Now to where it gets ugly: credit card debt.
85
And to say it's just ugly would still be a massive understatement.
86
Because it's not just ugly, it's dangerous.
87
Credit card balances in the United States have now crossed one trillion dollars, which is once again the highest level recorded in history.
88
And credit card debt has risen by more than half since 2020.
89
To add some more context, Americans have added more credit card debt in the last four
90
years than they did in the entire decade following the 2008 financial crisis.
91
And we're not just swiping like lunatics.
92
We're also opening accounts like there's no tomorrow.
93
The number of active credit card accounts has risen 20 % from levels seen before the pandemic, and now exceeds 600 million.
94
And with roughly 340 million individuals in the United States, that means the average American is managing several cards, several monthly payments and several financial headaches.
95
And here's where things start to fall apart.
96
Credit card delinquencies are rising fast.
97
The share of credit card accounts in serious delinquency has now climbed above 12%, which marks the highest level since the 2008 financial crisis.
98
And it's not hard to see why.
99
Over the last few years, inflation has soared, housing costs have reached record highs, and wages haven't come close to keeping up.
100
And here's the cherry on top.
101
The average interest rate on credit cards is now more than 21%, once again hovering around the highest level ever recorded.
102
So that means the 12 % of credit card users who are already delinquent aren't just behind.
103
they're likely drowning in compound interest.
104
And just when it seemed like things couldn't get any more chaotic, a new force arrived on the scene.
105
You've probably seen the buttons.
106
Buy now and pay over time with Affirm.
107
Pay in four installments with Klarna
108
and whatever other soft -colored slogans Silicon Valley could dream up to convince individuals
109
that borrowing money is a form of financial empowerment.
110
But here's the truth.
111
This concept is an innovation.
112
It's a marketing makeover and it's credit disguised as convenience.
113
It's a shiny new way to train an entire generation in normalized debt.
114
In fact, a recent study found that 15 % of all Americans use Buy Now Pay later in 2024, with 40 % of them regretting it after realizing the total costs.
115
And even worse, 24 % of these users have made a late payment, which is up from 18 % in 2023.
116
It's the same old credit trap, just this time with a better user interface.
117
So while headlines keep celebrating that consumer spending remains strong, the reality is people are financing their day -to -day survival one installment plan at a time.
118
And when you start to look at the American economy from a debt -first perspective, everything starts to look a whole lot different.
119
It doesn't look like the booming economy everyone's talking about on CNBC.
120
It looks more like a giant game of hot potato where everyone's hoping the music doesn't stop.
121
Every record high stock market headline, every flashy consumer spending report, it's all built on borrowed money.
122
Because the truth is, America isn't saving for the future, it's financing the present.
123
And that's what makes the credit crisis so dangerous.
124
It's not loud, it's not sudden, and it's not dramatic.
125
It's quiet, it's gradual, and it's happening in plain sight.
126
So yeah, everything appears to be fine on the surface.
127
The markets are high, inflation's easing, and unemployment's low.
128
But underneath, the foundation is beginning to crack.
129
Because this is America, a country that's surviving on debt.

앱 다운로드

유창하게 말하는 데 필요한 모든 것

AI 발음 평가문장마다 점수 확인
IPA 발음 연습모든 소리 마스터
단어 학습나만의 단어장 만들기
단어 게임놀면서 외우기

같은 채널

FOR YOU

추천 영상

이 클립이 영어 회화 연습에 좋은 이유

이 비디오는 일상적인 주제가 아닌 경제 관련 내용을 쉽게 풀어내고 있어, 실제 상황에서 복잡한 주제를 다루는 영어 실력을 키우기에 좋습니다. 특히 "drowning in debt"처럼 생동적인 표현과 "duct tape holding the economy together" 같은 비유가 많아, 영어의 표현력을 풍부하게 배울 수 있습니다. 또한, 구어체와 준격식체가 적절히 섞여 있어 IELTS 스피킹 준비에도 도움이 됩니다. 유튜브 영어 공부로 이 클립을 활용한다면, 단순히 듣는 것 이상으로 말하기의 리듬과 강세를 익힐 수 있습니다.

자연스러운 표현 분석

  • "Everything seems to be going great." - "모든 게 잘 되고 있는 것 같아"라는 직역보다 "모든 게 순조롭게 진행되고 있어"처럼 자연스럽게 표현할 수 있습니다. "going great"는 일상에서 자주 사용되는 간결한 표현으로, 회화에서 자연스러운 흐름을 만듭니다.
  • "The real issue is that the rest of America is looking at this reckless spending and saying, 'Hey, that looks kind of fun.'" - "진짜 문제는 미국의 다른 사람들이 이 무모한 지출을 보고 '이거 재밌어 보이네'라고 말하고 있다는 거야"라는 구조는 "the real issue is that..."로 주제를 강조하며, 직접 인용구를 넣어 구체성을 더합니다. 이렇게 하면 말하기에서 주요 내용을 명확히 전달할 수 있습니다.
  • "Debt has become the duct tape holding the entire economy together." - "부채는 경제를 유지하는 덕트 테이프가 됐어"라는 비유는 상상력을 자극하며, 복잡한 개념을 쉽게 설명합니다. 비유적 표현은 영어 회화 연습에서 중요한 요소로, 듣는 사람의 관심을 끌고 기억에 남게 합니다.

연습 루틴: 쉐도잉과 녹음 반복

영어 쉐도잉을 하기 위해선 다음 단계를 따라해 보세요. 1. 비디오를 5초씩 재생하며 즉시 따라하기. 이때 발음, 강세, 리듬을 최대한 흉내냅니다. 2. 자신이 말한 것을 녹음한 후 원본과 비교해 차이점을 찾습니다. 특히 "reckless spending"나 "service the interest" 같은 어구의 발음을 확인하세요. 3. 1분 길이의 구간을 선정해 완벽하게 따라할 때까지 반복합니다. 이 과정을 통해 shadow speech 기술을 익히면, 자연스러운 영어 발화가 가능해집니다. 매일 10분씩坚持하면, 2주 후에는 분명한 진전을 느낄 수 있습니다.

이 영상의 문법

화자가 가장 많이 쓰는 문형을 영상 속 실제 표현과 함께 정리했습니다.

문형영상 속 표현
현재완료 have/has + 과거분사 — 과거의 일이 지금도 관련이 있을 때has become · has exploded · have you ever heard
수동태 be + 과거분사 — 누가 하는지보다 무슨 일이 일어나는지에 초점is really just fueled · can be applied · is created
관계절 who / which + 절 — 사람이나 사물에 대한 추가 정보dollars, which is · payment, which is

쉐도잉이란? 영어 실력을 빠르게 키우는 과학적 방법

쉐도잉(Shadowing)은 원래 전문 통역사 훈련을 위해 개발된 언어 학습 기법으로, 다언어 학자인 Dr. Alexander Arguelles에 의해 대중화된 방법입니다. 핵심 원리는 간단하지만 매우 강력합니다: 원어민의 영어를 들으면서 1~2초의 짧은 지연으로 즉시 소리 내어 따라 말하는 것——마치 '그림자(shadow)'처럼 화자를 따라가는 것입니다. 문법 공부나 수동적인 청취와 달리, 쉐도잉은 뇌와 입 근육이 동시에 실시간으로 영어를 처리하고 재현하도록 훈련합니다. 연구에 따르면 이 방법은 발음 정확도, 억양, 리듬, 연음, 청취력, 말하기 유창성을 크게 향상시킵니다. IELTS 스피킹 준비와 자연스러운 영어 소통을 원하는 분들에게 특히 효과적입니다.

섀도잉 방법: 단계별 전체 가이드 읽기 →