Shadowing Practice: The $2.5 Trillion Credit Wave Nobody Sees Coming - Learn English Speaking with Video

Elige un modo de práctica

Cada modo abre una sala de práctica a pantalla completa.

213 oraciones
Si las oraciones son demasiado cortas o largas, haz clic en Editar para ajustarlas.
1
The 30 -year Treasury yield just hit the highest level since 2007.
2
And if you're thinking, cool, who cares?
3
Well, you're not alone.
4
Because treasury yields sound like the kind of thing that only matters to men in Patagonia Vest, who drink $8 iced lattes and talk about risk -adjusted returns at dinner parties.
5
But the reality is, hidden inside that number is the price of money.
6
Because that single number helps determine the borrowing cost on trillions of dollars of debt.
7
And for the first time since 2007, it's flashing a signal we haven't seen in nearly two decades.
8
causing underneath the surface.
9
And that damage is starting to surface in a $2 trillion asset class where the cracks are becoming harder to ignore.
10
But here's the part that's strange: even as interest rates are rising at the fastest pace in recent history, and signs of credit stress are materializing in the data,
11
many of the players in the industry are still selling the idea that everything is under control, that this is all overblown, and the market remains as healthy as ever.
12
But the reality is: those two things can't coexist.
13
And that's what makes this so interesting, because this story has only just begun, and it's quietly unfolding right in front of our eyes in real time.
14
The "hush -hush" surrounding all this is by design.
15
But to understand what's happening, we need to back up.
16
And we have to start with that one number from earlier.
17
Because when the 30 -year Treasury spiked to over 5%, the United States had at least one thing going for it.
18
At least there was company.
19
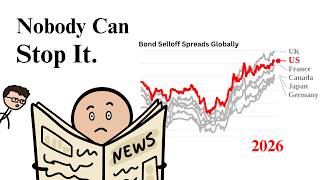
Because the UK's 30 -year just climbed to its highest level since 1998, while Germany's 30 -year reached its highest level since 2011.
20
but Japan's 30 -year is now sitting at an all -time high. So
21
when four of the largest sovereign bond markets in the world
22
start doing their best impression of Dogecoin after an Elon Musk tweet, it raises one very important question: What the fk is happening?
23
Because the bond market's supposed to be boring, it's supposed to be predictable, uneventful, and something your grandpa falls asleep watching.
24
And that's why it often gets labeled as the "adult in the room".
25
But right now, while everyone's distracted watching stocks go vertical and the AI hype, the adult in the room quietly just pulled the plug on the party.
26
And before we get into what higher yields actually mean for the economy, and why investors are quietly freaking out,
27
it's worth taking 30 seconds to explain what makes a bond yield move in the first place.
28
Because the movement in the yields is the real story.
29
What matters is the underlying mechanics of why they moved.
30
The number you see in the headlines is just the symptom.
31
And in its simplest form, a bond is just an "I owe you." It can be the government, a company, or anyone who wants to borrow money.
32
They issue a piece of paper that promises to pay back a fee fixed amount at a fixed maturity date.
33
People bid for that paper, and the price those buyers are willing to pay determines the yield.
34
So the relationship between a bond's price and its yield are inversely related.
35
If buyers are scrambling to buy the bond, the price gets bid up and the yield falls.
36
If buyers aren't interested, the price has to drop to attract new buyers, and the yield rises.
37
Price down, yield up.
38
Price up, yield down.
39
That's the relationship between buyers are demanding a higher return before they'll lock their money up.
40
And that happens for four main reasons.
41
First, the Federal Reserve.
42
The Fed sets the baseline interest rate for the entire economy.
43
So if the Fed raises the baseline rate to 5%, nobody wants an old bond paying just 3%.
44
So to get rid of that old bond, sellers have to slash its price until its yield matches the new rate environment.
45
Second, inflation.
46
If you think your dollars are going to be worth less when the bond matures, You want more return up front to compensate.
47
Supply.
48
The US has been issuing Costco -sized amounts of new debt every year.
49
At some point, the auction room starts running out of hands willing to go up.
50
So more supply means fewer eager buyers, which leads to prices falling and yields rising.
51
And fourth, demand foreign central banks, pension funds, sovereign wealth funds, the institutions that used to reliably show up at treasury auctions.
52
If they start to doubt that the US can pay back its nearly $40 trillion of debt, well, they start to pull back.
53
And if that happens, the price has to drop until someone is finally willing to walk in.
54
And what makes bond yields a favorite for economists is each maturity tells a different part of the story.
55
Each maturity sends a different signal about the economy.
56
will do in the near term.
57
The 10 -year is the favorite.
58
It's the global benchmark.
59
Almost every other rate, across asset classes, gets anchored to it.
60
And the 30 -year?
61
Well, it's the rate that asks the question: do you actually trust the United States fiscal situation long -term?
62
It prices three decades of inflation, three decades of deficits, and three decades of United States fiscal decisions.
63
But while the long end of the yield curve is sitting at levels we haven't seen in nearly two decades, that's actually not even the scariest part,
64
But if there's one thing the Federal Reserve has mastered, it's taking today's problems and handing them to tomorrow.
65
But there's some problems that can't be passed off.
66
Because what's causing the real pain right now is on the other end of the yield curve: the short end.
67
And it's the short end that the Fed has their little greasy fingerprints all over.
68
But before we get into that, a quick pause, because here's a number that stuck with me.
69
every single day.
70
And that was before the first iPad existed.
71
Imagine what that number looks like now.
72
So if you're like me, your Notes app is a graveyard of half -finished thoughts, and your voice memos are ramblings you never replay.
73
Which brings us to the sponsor of today's video, Plod.
74
With the PlodNote Pro, you can transcribe your conversations, calls, and notes into clear summaries and searchable insights.
75
And it's not just for audio either.
76
With Plod's unique multimodal input, you can add text and images too, so the full context lives in one place.
77
So for a video like this one, I can simply ask Plod: "What was the relationship between a bond's price and its yield?" There's no more digging through notes, no more hunting for information.
78
It's the answers you need, when you need them.
79
PLOD is the solution for a world where you're taking in more than 100 ,000 words
80
and 34GB of information every single day, and with a 4 .9 star rating and more than 2 million users globally, PLOD's track record speaks for itself.
81
So if you're tired of losing track of the ideas, conversations, and details you swore you'd remember, you can try out PLOD using the link below and get a free 30 -day money -back guarantee.
82
Thank you to PLOD for sponsoring this video.
83
And now back to the rate that's causing all the panic right now.
84
And that rate is called the SecureDuty overnight financing rate, or SOFR.
85
You can think of it as the overnight receipt for the entire US financial system.
86
It's a single number, published every morning, that tells the market what overnight borrowing actually cost the day before, based on real transactions.
87
It's not a guess or a target rate.
88
It's based on actual trades that have been cleared and settled.
89
And in early 2022, SOFR was effectively zero.
90
Then the Fed started hiking, and by mid -2023, Even after a year and a half of rate cuts,
91
it's still sitting higher than where we were before the pandemic.
92
And when rates rise this aggressively, there's consequences.
93
Because when most people think about debt, they think fixed rate.
94
Like a mortgage.
95
You lock in an interest rate on day one, the rate environment can do whatever it wants afterward, and your payment doesn't change.
96
But there's an entire other category of debt called floating rate, which works the opposite way.
97
A floating rate loan doesn't pick a fixed rate at origination.
98
SOFR, and then it adds a spread on top.
99
That spread is the lender's premium for taking on the risk.
100
With floating rate loans, the interest rate on the loan is directly tied to the benchmark it's pegged to.
101
So if SOFR moves, the interest rate on the loan moves too.
102
Meaning if SOFR rises, the borrower's interest on the debt rises.
103
And I think you can see where I'm going with this.
104
This is where the consequences of rapidly rising rates begin to show up.
105
And to see where the impact lands,
106
we need to follow the money a little They hit the weird middle market of the credit world.
107
It's loans for companies that are too large for a local small business loan, too small to issue public bonds on Wall Street, or too complex for a traditional bank to feel comfortable underwriting.
108
So these companies are forced to go to private lenders to borrow money, and these private credit loans have two key characteristics that help explain everything that's happening.
109
The first is that these loans almost never trade.
110
These are loans that happen in the dark.
111
There's no public price.
112
Nobody marks it ever every morning.
113
The loan's value is appraised on a predetermined schedule, usually once a quarter.
114
And we'll get more into why this is so important later.
115
The second is that the vast majority of these private credit loans are floating rate.
116
And that floating rate feature is important to watch.
117
Because remember, on a floating rate loan, when the benchmark moves up, the borrower's interest on the loan moves with it, meaning the loan becomes more expensive to service,
118
the borrower pays more, cash flows get tighter, and the margin for error shrinks, which becomes a problem for private credit loans private credit lenders,
119
because their returns depend on those payments continuing to arrive on time.
120
And the problems have already started, and they're unraveling in real time as you watch this video.
121
In 2021, a software company called Pluralsight was acquired by private equity firm Vista Equity Partners.
122
And Vista did what private equity firms do: they funded the acquisition with a few billion dollars of equity, and then over a billion dollars in private credit loans,
123
for a total price tag of over $3 billion.
124
the acquired company takes on the debt.
125
So Pluralsight's balance sheet went from its own independent structure to
126
suddenly carrying over a billion dollars of new debt from private credit.
127
And this debt just happened to be in the form of floating rate loans pegged to SOFR.
128
Which was fine.
129
For about three years, because while SOFR was still near zero, the math worked.
130
But then, SOFR went from 0 to over 5%.
131
And suddenly, Pluralsight was underwater.
132
And by August 2024, it was over for Pluralsight.
133
Their interest payments were now unsustainable.
134
And a group of private credit lenders were forced to step in, convert their debt to equity, and inject an additional $275 million of new money into the business.
135
And as their reward for doing so, they took 85 % of the company.
136
market.
137
Which brings us to a quote I came across while researching for this video, and if I'm being honest, it might be a new personal favorite of mine.
138
Because in J .P.
139
Morgan's third quarter earnings call from 2025, when CEO Jamie Dimon was asked about the cracks in the credit market, he responded, "When you see one cockroach,
140
there are probably more." Which is hilarious for so many reasons, but it's also true.
141
And it's also exactly what the data is showing us.
142
Because earlier this year, the Fitch private credit default rate, which tracks more than 1 ,500 middle market private credit borrowers, hit 6 % on its trailing 12 -month measure,
143
which is the highest rate recorded since inception.
144
And the reason that number is significant is the scale behind it.
145
Because the private credit market has exploded in recent years, up almost tenfold since 2007.
146
And like I mentioned earlier, it's an industry where the foundation of the market is going
147
to be a big deal is built on these floating rate loans.
148
Which matters because Pluralsight wasn't unique.
149
It was just one borrower in a massive stack.
150
And most of that stack is borrowing off SOFR, just like Pluralsight did, which means nearly all the companies
151
that borrowed from private credit just absorbed the same compounding rate shock as Pluralsight.
152
So, how is it possible that the data is showing record defaults
153
while everyone in the industry is acting like things are all good?
154
And the answer is… sneaky accounting.
155
More specifically, one of the more creative accounting structures the finance industry has ever produced.
156
Because if there's one thing the finance industry excels at, no pun intended, it's taking something that started as a reasonable idea
157
and letting greed take over in a way that would make the Rockefeller family blush.
158
So, what exactly are they doing, you ask?
159
Well, it's called a payment -in -kind feature, or a PIC, and it lets a borrower make interest payments on a loan in a form other than cash,
160
which I can't even believe that's something I'm saying out loud, considering interest is supposed to be the cash return a lender earns for lending money.
161
So what happens in a world where SOFR jumps from zero to over 5%, the interest payments on the loan get a whole lot more expensive, and the borrower can no longer keep up?
162
Well, that's where PICs come in.
163
option to pay in kind instead, which is the polite way of saying the borrower does not pay.
164
The unpaid interest then gets added onto the principal, and the balance owed at maturity grows.
165
Which is funny because normally in finance, when a borrower can't make the cash interest payments on a loan, that's classified as entering into default.
166
And the default is the trigger.
167
It's what lets the lender call the loan, force a restructuring, and start the slow walk toward bankruptcy court.
168
The that trigger.
169
Because with a PIC, when the borrower can't make the cash payment, the loan flips to be "paid in kind,"
170
and the interest owed just gets added to the balance instead of being paid with cash.
171
Which means, when there's a PIC, technically speaking, no payments were missed, and nothing defaulted, and the loan is still counted as performing, even when there was actually no cash received.
172
And when the lenders enter into these payment -in -kind arrangements, they report the unpaid interest as income,
173
meaning the interest that was never actually in cash is counted as income.
174
And don't worry, it gets even worse.
175
Because a significant portion of the private credit market operates through a type of investment vehicle called a business development company, or BDC.
176
These funds follow specific regulatory rules, and in exchange they get favorable tax treatment, including zero corporate income tax.
177
But to keep that tax status,
178
they are legally required to distribute at least 90 % of their taxable income to investors. is reported as income?
179
Well, here's what all this looks like.
180
A company sliding toward insolvency shows up on the books as a healthy, income -generating asset.
181
The interest it cannot pay gets capitalized into the principal.
182
The fund reports that capitalized interest as income.
183
And because the fund is legally required to distribute 90 % of its taxable income,
184
it mails out a cash dividend to investors on money it never actually collected.
185
So, the gets, the more interest they owe to the lender, the more income the private credit fund reports,
186
and the larger the dividend it must send out, on cash that was never actually collected.
187
And that's the sneaky accounting.
188
And it's been spreading rapidly.
189
Around 11 .5 % of private credit loans now include PIC features, which is an increase of more than 72 % since the end of 2021.
190
And more than half of those were classified as "bad PICs," meaning the PIC feature was not part
191
after the borrower started struggling.
192
And across the public funds in this asset class, meaning the business development companies, PICS run on average around 8 % of the fund's income.
193
Meaning roughly 8 cents of every dollar these funds report as income is interest nobody actually paid in cash, and there's examples where it's much worse.
194
Like FSKKR, who is running PICS at more than 14 .5 % of their total investment income.
195
And their non -accrual loans, meaning loans where borrowers have stopped making payments entirely, reached over 5%.
196
And it's just like Jamie Dimon said on that October earnings call: "When you see one cockroach, there are probably more." Because earlier this year,
197
Fitch recorded 11 default events in a single month, nearly double the 2025 monthly average of 5 .9.
198
And of those 11 defaults, more than 60 % of them involved the introduction of payment -in -kind interest instead of cash interest payments.
199
And there's still one final layer to all this.
200
It's not just about how the income gets reported, it's also about how the loans themselves get valued.
201
Since these loans don't trade on any exchanges, and there's no public market price you can just look up, they fall under an accounting label called Level 3,
202
which is the most illiquid and subjective category of asset measurements in financial reporting.
203
It's a label that shows it relies entirely on unobservable inputs and internal models, rather than active market data.
204
found that more than 10 % of private credit loans were already marked down by at least 50 cents on the dollar.
205
And that's how a tidal wave has been quietly building in the background, and it's what people are calling the private credit maturity wall,
206
It's a wall of roughly $85 billion in BDC loan maturities coming due between 2026 and 2029,
207
and when that hits, these companies will have to refinance at today's rates.
208
And when all this near -zero debt has to roll at today's rates, someone has to face the consequences.
209
And if you want to watch when this actually hits, and not just read about it afterward, subscribe.
210
Because this story is still in the early innings, and I'll be covering it closely as it unfolds.
211
Because the truth is, you may be able to hide a loss in an accounting line, you can roll unpaid interest into a bigger principal, and you can even call a distressed borrower a performing loan.
212
But the math is still the math.
213
And bad math doesn't just disappear.

Descargar app

Todo lo que necesitas para hablar con fluidez

Pronunciación con IAEvalúa cada oración
Práctica de IPADomina cada sonido
VocabularioConstruye tu banco de palabras
Juego de vocabularioAprende mientras juegas

Mismo canal

FOR YOU

Recomendar Video

Vocabulario y notas de pronunciación para esta lección

Esta lección de conversación de nivel B2 se basa en el vídeo “The $2.5 Trillion Credit Wave Nobody Sees Coming”. Las palabras que más se repiten: rate, loan, interest, credit, private. Este vídeo tiene 213 frases y 3126 palabras para practicar shadowing. La parte hablada dura 17:27. El hablante habla a un ritmo natural de unas 179 palabras por minuto, cercano a una conversación cotidiana. El 83 % de las palabras está entre las 3.000 más comunes del inglés; conviene repasar el resto antes de empezar.

Vocabulario clave de este vídeo

Las 15 palabras más avanzadas del vídeo, con su pronunciación y significado:

PalabraPronunciaciónSignificado
yield verbo/jiːld/producir, dar
borrower sustantivo/ˈbɑɹoʊɚ/prestatario
float verbo/fləʊt/flotar
lender sustantivo/ˈlɛn.dɚ/prestador
buyer sustantivo/ˈbaɪ.əɹ/cliente, clienta
maturity sustantivo/məˈtjʊəɹɪti/madurez, vencimiento
quietly adverbio/ˈkwaɪ.ɪt.li/mansamente, despacio
mathematics sustantivo/mæθ(.ə)ˈmæt.ɪks/matemáticas, matemática
benchmark sustantivo/ˈbɛn(t)ʃmɑːk/cota de referencia, estándar de comparación
unpaid adjetivo/ʌnˈpeɪd/no remunerado
investor sustantivo/ɪnˈvɛs.tə(ɹ)/inversionista, inversor
borrow verbo/ˈbɑɹ.oʊ/pedir prestado, tomar prestado
consequence sustantivo/ˈkɑn.sɪ.kwəns/consecuencia
overnight adverbio/əʊvə(ɹ)ˈnaɪt/de un día para otro, de la noche a la mañana
capitalize verbo/ˈkæpətəˌlaɪz/escribir en mayúsculas, escribir con mayúscula inicial

Phrasal verbs que vas a escuchar

PalabraPronunciaciónSignificado
pay back verbo/peɪ bæk/devolver
back up verboretroceder, ciar
come across verbopasarse a
go up verbosubir
keep up verbocontinuar con, continuar así
look up verbo/ˌlʊk ˈʌp/mejorar
show up verbocomparecer, personarse
try out verboprobar, ensayar

Gramática en este vídeo

Las estructuras que más usa el hablante, con las palabras exactas del vídeo:

EstructuraEn el vídeo
Present perfect continuous have/has been + -ing — una acción que empezó antes y continúahas been issuing · it's been spreading
Present perfect have/has + participio pasado — una acción pasada que sigue importando ahorahaven't seen · has only just begun · has mastered
Voz pasiva be + participio pasado — importa lo que ocurre, no quién lo hacecan't be passed · is called · have been cleared
Oraciones de relativo who / which + oración — información extra sobre una persona o cosaanyone who wants · did, which means · instead, which is

Pronunciación a tener en cuenta

El hablante usa 27 contracciones y formas reducidas, como can't, you're, doesn't. Dilas en su forma corta, tal como las oyes.

  • Los sonidos de “th”: mathematics /mæθ(.ə)ˈmæt.ɪks/, underneath /ˌʌndɚˈniθ/
  • Los sonidos de “sh” y “zh”: benchmark /ˈbɛn(t)ʃmɑːk/, hush /hʌʃ/, inflation /ɪnˈfleɪ.ʃən/, blush /ˈblʌʃ/, inception /ɪnˈsɛpʃən/
  • Palabras largas — cuida el acento: maturity /məˈtjʊəɹɪti/, mathematics /mæθ(.ə)ˈmæt.ɪks/, capitalize /ˈkæpətəˌlaɪz/, favourable /ˈfeɪv(ə)ɹəbəl/, predictable /pɹəˈdɪktəbləl/

Sonidos difíciles para hispanohablantes:

  • s + consonante al inicio — sin añadir una “e” delante: sneaky /ˈsniːki/, stack /stæk/, sponsor /ˈspɒn.səː/
  • /v/ — no es /b/: los dientes tocan el labio inferior: investor /ɪnˈvɛs.tə(ɹ)/, overnight /əʊvə(ɹ)ˈnaɪt/, dividend /ˈdɪvɪdɛnd/, sovereign /ˈsɑv(ə)ɹɪn/, curve /kɚv/
  • /z/ — sonora, no /s/: capitalize /ˈkæpətəˌlaɪz/, appraise /əˈpɹeɪz/, pause /pɔːz/

Cómo practicar con este vídeo

  1. Escucha el vídeo entero una vez sin hablar y anota las palabras que no conoces.
  2. Empieza a velocidad 0,75×, haz shadowing frase por frase y vuelve a la velocidad normal cuando te resulte fácil.
  3. Grábate y compara con el original, prestando atención a palabras como yield, borrower, float.

¿Qué es la Técnica de Shadowing?

Shadowing es una técnica de aprendizaje de idiomas respaldada por la ciencia, desarrollada originalmente para la formación de intérpretes profesionales y popularizada por el políglota Dr. Alexander Arguelles. El método es simple pero poderoso: escuchas audio en inglés nativo y lo repites en voz alta de inmediato, como una sombra que sigue al hablante con solo 1-2 segundos de retraso. A diferencia de la escucha pasiva o los ejercicios de gramática, el shadowing obliga a tu cerebro y músculos de la boca a procesar y reproducir simultáneamente patrones de habla reales. Las investigaciones muestran que mejora significativamente la precisión de la pronunciación, la entonación, el ritmo, el habla conectada, la comprensión auditiva y la fluidez al hablar, convirtiéndola en una de las metodologías más efectivas para la preparación del IELTS Speaking y la comunicación en inglés en el mundo real.

Técnica de shadowing: lee la guía completa paso a paso →