Shadowing Practice: The Psychology Behind Your Spending Habits (And How to Fix it) - Learn English Speaking with Video

Choose a practice mode

Each mode opens a full-screen practice room.

645 sentences
If sentences are too short or too long, click Edit to adjust them.
1
Imagine this.
2
It's 1147 on a Tuesday night.
3
You've had a long day.
4
Work was exhausting.
5
You haven't really had a moment to yourself, and you're finally lying in bed with your phone.
6
You open a shopping app.
7
You're not looking for anything in particular.
8
You just want to see what's there.
9
And then you find it.
10
A pair of headphones.
11
A jacket.
12
Maybe some gadget that promises to make your life a little easier.
13
You look at the price.
14
It's not exactly cheap.
15
You hesitate for a second.
16
Then you see the words, limited time offer.
17
And suddenly, something changes.
18
You start imagining yourself using it.
19
You picture how much better your mornings might be.
20
How much more organized your life could become.
21
How good it would feel to finally own something you've been thinking about.
22
You tap buy now.
23
And for a brief moment, you feel better.
24
Not because you've received the product.
25
You haven't.
26
Not because your life has actually changed.
27
It hasn't.
28
but something inside you feels satisfied.
29
Now let's jump forward three weeks.
30
The package is sitting in a corner of your room.
31
You barely use the thing.
32
And when you look at your credit card statement, you wonder why you bought it in the first place.
33
The strange part is, you probably knew, even before you purchased it, that you didn't really need it.
34
So why did you do it?
35
Why do we sometimes spend money on things we don't even want that much?
36
Why does a discount feel like an opportunity, even when the purchase wasn't in our plans?
37
Why can we be perfectly reasonable with money in the morning, then make a completely different decision at night?
38
And why does the same person who carefully compares prices at the grocery store
39
sometimes spend hundreds of dollars on something they saw in a 30 -second video?
40
Most people will tell you that the answer is poor discipline.
41
They'll say you need a budget, and they'll tell you to stop buying unnecessary things, cut back on your coffee, and start saving.
42
And yes, those things can help.
43
But they don't explain why you keep making the same decisions even when you know better.
44
Because spending money isn't just a financial decision.
45
It's an emotional decision.
46
It's a social decision.
47
And sometimes, it's a decision about the person you wish you were.
48
Today, we're going to look at the psychology behind your spending habits.
49
Why your brain sometimes treats spending as a reward.
50
Why certain purchases feel more valuable than they really are.
51
How advertising and social pressure influence your decisions.
52
And five practical ways to take control of your money without turning your life into one long exercise in deprivation.
53
Because the goal isn't to stop enjoying your money.
54
It's to stop spending it in ways you don't actually enjoy.
55
Let's get into it.
56
One, your brain doesn't always buy the product.
57
Let's start with something that might change how you look at shopping.
58
When you buy something, you're not always buying the thing itself.
59
Sometimes, you're buying what you believe the thing will do for you.
60
Think about the last time you purchased something you didn't really need.
61
Maybe it was a new outfit.
62
Maybe it was an expensive phone.
63
Maybe it was a piece of equipment for a hobby you were convinced you were about to take seriously.
64
What were you actually looking forward to?
65
Was it the object?
66
Or was it the feeling you imagined having once you owned it?
67
There's a difference.
68
A new outfit might represent confidence.
69
A new phone might represent being successful.
70
A new set of workout equipment might represent becoming the person who finally takes their health seriously.
71
And that last one is particularly interesting.
72
Because sometimes, we buy things for the version of ourselves we hope to become.
73
You buy the running shoes before you've started running.
74
You buy the expensive notebook before you've started writing.
75
You buy the kitchen equipment before you've developed the habit of cooking.
76
And for a moment, buying the equipment feels like making progress.
77
You've taken action.
78
You've invested in yourself.
79
You've made a commitment.
80
Except, you haven't actually done the difficult part yet.
81
You've purchased the symbol of the change.
82
And the symbol can feel surprisingly satisfying.
83
This is one reason spending can become so emotionally powerful.
84
The product isn't just sitting there in your imagination.
85
It's carrying a whole story.
86
A story about who you could become.
87
And the more attractive that story is, the easier it becomes to justify the purchase.
88
Now, this doesn't mean every purchase connected to a goal is a bad purchase.
89
If buying a good pair of running shoes helps you exercise comfortably, that's a perfectly reasonable decision.
90
The problem begins when the purchase itself becomes the substitute for the behavior.
91
You start confusing the feeling of getting ready with the experience of actually doing the work.
92
And this can happen in almost every area of life.
93
You buy another productivity app because you want to become organized.
94
You purchase another personal finance book because you want to get better with money.
95
You upgrade your camera because you want to become a better creator.
96
And slowly, you end up spending money on the identity of a person you haven't yet become.
97
Here's a question worth asking before your next purchase.
98
Am I buying something that helps me do the thing?
99
Or am I buying the feeling of being someone who does the thing?
100
That question alone can reveal a surprising amount about your spending habits.
101
But there's another psychological mechanism that makes these purchases even more tempting.
102
And it has to do with how your brain experiences money leaving your hands.
103
2. Why spending money can feel strangely painless
104
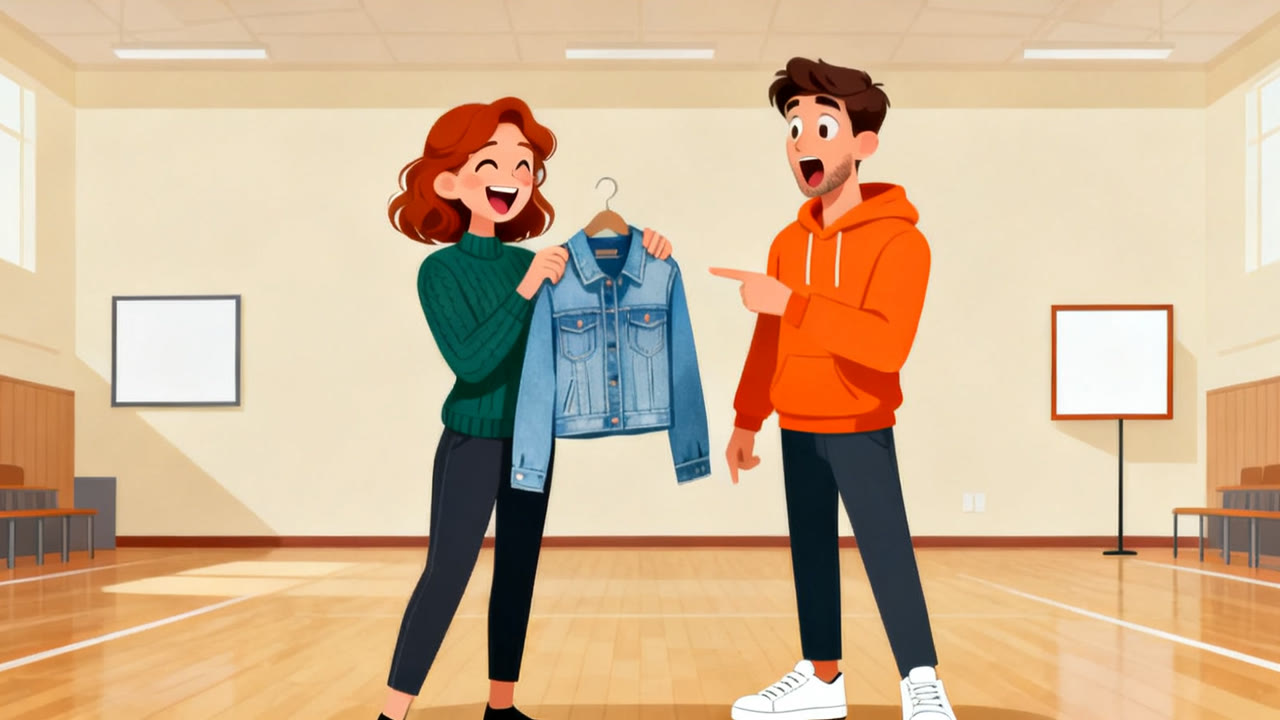
Imagine buying a $100 item in two different ways.
105
In the first situation, you take a $100 bill out of your wallet and hand it to someone.
106
You watch the money leave.
107
It's gone.
108
In the second situation, you tap your phone, the payment goes through, and you walk away.
109
Same amount, same purchase, but the experience can feel very different.
110
When you physically hand over cash, the loss is immediate and visible.
111
When you use a card or a digital payment, the transaction can feel much less concrete.
112
You don't see your money disappearing in the same way.
113
You see a screen, a confirmation message, a little checkmark, and then you're done.
114
Researchers have studied a concept known as the pain of paying.
115
It's the unpleasant feeling associated with giving up money.
116
That feeling can influence how much we're willing to spend.
117
When the payment feels more immediate and noticeable, people may become more aware of the cost.
118
When the payment feels distant or less tangible, spending can become easier.
119
And this is particularly relevant in a world where almost everything can be purchased with a single tap.
120
You can order dinner without looking at your bank account.
121
You can buy a new phone without taking money out of your wallet.
122
You can subscribe to a service and forget
123
that it exists until months later the transaction has become so convenient that the financial consequence can feel almost invisible.
124
The problem isn't that credit cards are automatically bad.
125
Credit cards can be useful.
126
They can offer protections, convenience, and rewards when managed responsibly.
127
The problem is when the convenience of paying becomes disconnected from the reality of spending.
128
You experience the pleasure of the purchase today, but the financial consequence arrives later.
129
And by the time it arrives, the emotional experience of buying something may already be gone.
130
Think about how often you make a purchase and immediately move on.
131
You don't sit there thinking about the $80 you just spent.
132
You go back to your day.
133
But the money is still gone.
134
And if you make enough purchases like that, they can quietly add up.
135
A $15 subscription here.
136
A $35 delivery order there.
137
A $60 purchase because something was on sale.
138
Each one feels small in isolation.
139
Together, they can become a meaningful amount of money.
140
This is why one of the most useful things you can do is reconnect the purchase with its actual cost.
141
Not by making yourself feel guilty.
142
Not by treating every dollar you spend as a mistake.
143
Simply by making the financial consequence visible again.
144
Before you buy something, pause and ask, If I had to hand over this amount in cash right now, would I still want it?
145
You might still say yes, and that's fine.
146
But if the answer changes when you imagine the money leaving your hands, you've learned something important about the purchase.
147
The convenience of the transaction may have been doing more of the work than you realized.
148
And that brings us to another reason spending can become difficult to control.
149
Because sometimes, the thing you're trying to purchase isn't a product.
150
It's relief.
151
3. When shopping becomes an emotional escape
152
Let's talk about a very ordinary moment.
153
You've had a difficult day.
154
Maybe your boss criticized your work.
155
Maybe you've been dealing with family responsibilities.
156
Maybe you feel exhausted, lonely, or simply bored.
157
You get home, you sit down, and you start scrolling.
158
You weren't planning to buy anything, but then you see something you like.
159
You imagine owning it.
160
You feel a little excitement.
161
You make the purchase, and for a moment, the day feels less difficult.
162
This is where spending can become connected to emotional regulation.
163
In other words, you begin using shopping to change how you feel.
164
Research on impulsive buying has found that emotions and mood regulation can play a role in purchasing behavior.
165
A large body of research has explored how people may use buying to seek positive feelings or reduce negative ones.
166
And this makes sense when you think about it.
167
When you're stressed, you want relief.
168
When you're bored, you want stimulation.
169
When you're feeling low, you want something that gives you a little lift.
170
And shopping can offer a quick, accessible way to experience those feelings.
171
But here's the catch.
172
The relief may not last.
173
The emotion that led you to make the purchase may still be there afterward.
174
You might feel excited when the order is placed.
175
Then the excitement fades, and the original problem is still waiting for you.
176
Your stressful job is still stressful.
177
Your loneliness hasn't disappeared.
178
Your exhaustion hasn't been solved.
179
So you may find yourself looking for another little lift. And another. And another.
180
Over time, the pattern can become surprisingly automatic.
181
You feel bad, you shop.
182
You feel better.
183
The feeling fades, you shop again.
184
And eventually, the purchase becomes less about what you're buying and more about what you're trying to escape.
185
Now, I want to be careful here.
186
Enjoying shopping does not automatically mean you have an unhealthy relationship with money.
187
Buying something enjoyable after a hard week can be perfectly reasonable.
188
The issue is whether spending has become your main way of dealing with difficult emotions.
189
Because if it has, you may be asking money to solve a problem it was never designed to solve.
190
And that can be expensive.
191
So here's a practical way to interrupt the pattern.
192
The next time you feel the urge to buy something unexpectedly, don't immediately ask yourself whether the item is worth the price.
193
Ask yourself a different question.
194
What am I feeling right now?
195
And what am I hoping this purchase will change?
196
Are you tired?
197
Are you frustrated?
198
Are you looking for a reward?
199
Are you trying to feel more in control?
200
Are you simply looking for something interesting to do?
201
You don't have to judge the answer.
202
You just have to recognize it.
203
Because once you can identify the emotion, you have more than one way to respond to it.
204
If you're exhausted, maybe what you need is rest.
205
If you're bored, maybe you need stimulation that doesn't involve spending.
206
If you're feeling unappreciated, maybe you need to acknowledge what you've been carrying instead of buying something to make the day feel better.
207
And sometimes, you may still decide to make the purchase.
208
But now, it's a conscious decision, not an automatic response to a feeling you haven't even noticed.
209
4. The discount that makes you spend more
210
Now let's look at one of the most interesting tricks your brain plays when it comes to money.
211
Imagine you're walking through a store.
212
You see a jacket.
213
It's marked down from $200 to $100.
214
You think, that's a great deal.
215
And you buy it.
216
But here's a question.
217
If that same jacket had simply been priced at $100 from the beginning, would you have purchased it?
218
Maybe, maybe not.
219
But the discount has changed how you evaluate the decision.
220
Instead of asking, is this jacket worth $100 to me?
221
You're thinking, I'm saving $100.
222
And that can make a purchase feel like a financial victory, even though you're still spending $100.
223
This is a form of reference point thinking.
224
Your brain doesn't always evaluate a price in isolation.
225
It compares that price with another number, the original price, the price your friend paid, the price you expected to pay,
226
or the price you believe the product should have.
227
And once that reference point is established, it can influence what feels like a good deal.
228
This is why a sale can feel exciting even when you weren't interested in the product before you saw it.
229
The discount creates a new reason to buy.
230
And suddenly, you're not just buying an item, you're taking advantage of an opportunity.
231
There's also a subtle sense of urgency.
232
You begin thinking, if I don't buy this now, I might miss out.
233
And the possibility of missing out can feel more uncomfortable than the possibility of spending money.
234
So you make the purchase.
235
Not because the product fits your needs, but because the deal seems too good to ignore.
236
Here's the problem.
237
A discount doesn't create value for you unless the item has value to you in the first place.
238
If you spend $100 on something you never wanted, you haven't saved $100.
239
You've spent $100.
240
And if you spend money on an item just because it's discounted, the discount has effectively made the purchase more expensive than doing nothing.
241
Think about that for a second.
242
The cheapest purchase is sometimes the one you don't make.
243
So the next time you see a sale, try asking yourself this.
244
If this item were not discounted, would I still be interested in buying it?
245
And here's an even better question.
246
If I walked away right now and never saw this deal again, would my life actually be worse?
247
If the answer is no, you probably don't need to rush.
248
A good financial decision doesn't become a bad one simply because you took a day to think about it.
249
But sales aren't the only thing that influence are spending.
250
Sometimes, the strongest influence isn't a price.
251
It's another person.
252
5. You're not just spending money.
253
You're keeping up.
254
Imagine opening social media and seeing someone you know.
255
They're on vacation.
256
They're wearing something expensive.
257
They're showing off a new car.
258
They're living in a beautiful apartment.
259
And you look at your own life.
260
Your apartment suddenly feels smaller.
261
Your clothes feel less impressive.
262
Your weekend feels a little less exciting.
263
Nothing about your actual life has changed, but your perception of it has.
264
And that change can influence how you spend.
265
Humans naturally compare themselves with other people.
266
We use other people's lives as reference points for understanding our own.
267
And when those reference points involve money, things can get complicated.
268
Because we don't always see the full financial picture.
269
We see the new car.
270
We don't see the monthly payment.
271
We see the vacation.
272
We don't see the credit card balance.
273
We see the beautiful home.
274
We don't see the years of savings, the debt, the family support, or the financial trade -offs behind it.
275
We're comparing our entire financial reality with someone else's carefully selected highlights.
276
And sometimes, we respond by trying to close the gap.
277
We buy clothes that make us feel more successful.
278
We spend money on experiences we don't really enjoy because we want to be part of the conversation.
279
We upgrade things that are perfectly functional because our current version suddenly feels outdated.
280
This is where spending becomes connected to status and identity.
281
A purchase can become a way of communicating something about yourself.
282
I'm successful.
283
I belong here.
284
I can afford this.
285
I'm not falling behind.
286
And there's nothing inherently wrong with wanting to look good or enjoy nice things.
287
The problem begins when your spending is determined by a standard that keeps moving.
288
Because there's always someone with a nicer car, a bigger house, a more expensive vacation, a newer phone.
289
And if your sense of financial success depends on matching what you see around you, you'll never really arrive.
290
There will always be another upgrade, another purchase, another person whose lifestyle makes yours feel insufficient.
291
So here's a question that can help you separate your own values from the pressure around you.
292
Would I still want this if nobody else could see that I owned it?
293
Would you still want the expensive watch?
294
Would you still want the designer bag?
295
Would you still want the luxury vacation?
296
If the answer is yes, that's useful information.
297
You may genuinely enjoy the thing.
298
But if the answer is no, then it's worth asking whether you're paying for the experience itself or for the reaction you hope it creates.
299
And here's something important.
300
You don't have to reject every social influence in your life.
301
You just need to recognize when someone else's definition of success is quietly becoming your financial priority.
302
Because the money you're spending to look successful is money you could have used to build a life
303
that actually feels successful to you.
304
And that brings us to one of the most dangerous spending patterns of all.
305
The belief that a future version of you will somehow take care of the consequences.
306
Six, the future version of you is paying for today's decisions.
307
There's a sentence that makes a lot of spending decisions feel reasonable.
308
I'll deal with it later.
309
Maybe you've said it yourself.
310
I'll pay off the credit card next month.
311
I'll start saving once I get my next raise.
312
I can afford this now.
313
I'll just cut back on something else.
314
And sometimes those plans work.
315
But sometimes, the future you're imagining is a little more optimistic than the reality you're going to face.
316
Because when you think about buying something today, the purchase is immediate.
317
The excitement is immediate.
318
The satisfaction is immediate.
319
But the financial consequences may feel distant.
320
Your next paycheck hasn't arrived.
321
Your next bill hasn't come due.
322
Your savings account hasn't been affected yet.
323
So your brain can treat the future cost as less urgent than the present reward.
324
This is related to a psychological tendency called present bias.
325
We often give greater weight to rewards we can experience now than to rewards or costs that arrive later.
326
And it's not just about money.
327
It's why we sometimes choose to watch another episode instead of going to bed, why we postpone exercise, why we delay difficult tasks.
328
The immediate experience feels more compelling than the future consequence.
329
And spending can take advantage of that tendency.
330
Consider a purchase that costs $600.
331
If you look at the full amount, you might hesitate.
332
But if the same purchase is presented as $50 a month, it can feel much easier to accept.
333
The total cost hasn't changed, but the way you experience it has.
334
And when you have several of these payments running at the same time, they can begin to compete for the same future paycheck.
335
The phone payment, the furniture payment, the subscription, the buy -now -pay -later purchase.
336
Each one may seem manageable by itself.
337
But your future income is not an unlimited resource.
338
It has already been assigned to things you haven't fully experienced yet.
339
And here's where I want you to be especially careful.
340
A payment plan isn't automatically a bad decision.
341
There are situations where spreading out a payment can be useful.
342
But the psychological danger is treating a smaller monthly payment as proof that the purchase is affordable.
343
Affordability isn't just about whether you can make this month's payment.
344
It's about whether the purchase fits your overall financial situation.
345
So when you're considering something expensive, try looking at the full amount first.
346
Not the monthly payment, not the promotional offer, not the amount you think you might earn next year.
347
The actual total.
348
Then ask yourself, if I had to pay the full amount today, would I still choose this?
349
And if the answer is yes, ask one more question.
350
What am I giving up by spending this money here?
351
Because every dollar has an opportunity cost.
352
The money you spend on one thing is money you can't use for something else.
353
It might be savings.
354
It might be paying down debt.
355
It might be a future experience that matters more to you.
356
You don't need to calculate the opportunity cost of every cup of coffee.
357
But for meaningful purchases, it's worth understanding what the money could otherwise do.
358
And once you start thinking this way, you'll notice something.
359
Many spending decisions become clearer when you stop asking whether you can afford the payment
360
and start asking whether you want to give up the money.
361
7. Why your budget keeps failing
362
Now let's talk about budgeting.
363
Because if you've ever created a budget, followed it for a few days, and then abandoned it, I want you to hear this.
364
The problem may not be that you're bad at budgeting.
365
The problem may be that your budget only understands your numbers.
366
But your spending habits are influenced by your behavior.
367
Imagine creating a budget that says $400 for groceries, $150 for dining out, $200 for entertainment, $300 for savings.
368
Everything looks reasonable.
369
You feel organized.
370
You feel in control.
371
Then Friday arrives.
372
You've had a difficult week.
373
Your friends invite you to dinner.
374
You order more than you planned.
375
You go somewhere afterward.
376
And suddenly, you've spent more than your entertainment budget allowed.
377
What happens next?
378
A lot of people respond with guilt.
379
They think, I messed up.
380
And because they feel like they've failed, they stop paying attention.
381
They stop tracking.
382
They stop checking the numbers.
383
And the budget becomes another thing they feel bad about.
384
But here's a different way to look at it.
385
Your budget told you how much you planned to spend.
386
It didn't tell you why you were likely to spend more.
387
Maybe dining out is how you maintain friendships.
388
Maybe Friday night is when you feel most exhausted.
389
Maybe you're spending increases when you're around certain people.
390
Maybe you consistently underestimate how much you enjoy certain experiences.
391
These are not just mathematical problems.
392
They're behavioral patterns.
393
And a useful budget needs to account for them.
394
If you know that you enjoy eating out with friends, pretending you'll never do it again probably isn't a sustainable strategy.
395
A more useful approach is to decide how much you're comfortable spending on it.
396
Then, make room for it.
397
Because a budget isn't supposed to punish you for enjoying your life.
398
It's supposed to help you make choices about how your money gets used.
399
And this is where an important psychological distinction comes in.
400
There's a difference between spending money deliberately and spending money automatically.
401
Deliberate spending is when you make a decision that reflects your priorities.
402
Automatic spending is when the situation makes the decision for you.
403
You see an offer.
404
You tap buy now.
405
You get a notification.
406
You order something.
407
You feel stressed.
408
You shop.
409
The purchase happens before you've really considered whether it belongs in your life.
410
The goal isn't to eliminate every spontaneous purchase.
411
It's to create enough space between the urge and the action that you can decide whether the purchase is actually worth it.
412
And that brings us to the practical part.
413
Because understanding your spending psychology is useful, but understanding it and changing it are two different things.
414
Eight, five ways to change your spending habits.
415
Strategy one, create a pause between wanting and buying.
416
The first strategy is simple.
417
Don't make every purchase the moment you want to make it.
418
When you feel the urge to buy something that wasn't already on your shopping list, introduce a waiting period.
419
For a small purchase, that might be 24 hours.
420
For a larger purchase, it might be a few days or even a week.
421
The exact amount of time isn't the important part.
422
The important part is separating the feeling of wanting something from the decision to own it.
423
Because desire can change.
424
You might see something online and feel strongly about it at 10 p .m.
425
By the next morning, you may barely remember it.
426
Or you may still want it, and that's useful information.
427
If you still want the item after waiting, you can evaluate it with a clearer head.
428
You can compare prices.
429
Check whether you already own something similar.
430
Think about how often you'll use it, and decide whether it fits your budget.
431
The waiting period isn't meant to stop you from buying things.
432
It's meant to stop the most temporary feelings from making permanent financial decisions.
433
Here's an easy way to implement it.
434
Create a wish list.
435
Whenever you want something that wasn't planned, put it on the list instead of buying it immediately.
436
Write down the item, the price, and the date you added it.
437
Then revisit the list after your waiting period.
438
You may discover that some things still feel worth buying, others will no longer interest you,
439
and every item you decide not to buy is money that stays available for something you value more.
440
The best part?
441
You don't have to fight the urge every single time.
442
You just have to follow the rule you created when you weren't in the middle of wanting something.
443
Strategy two, Give your spending a job
444
Here's a mistake people often make when trying to save money.
445
They treat saving as whatever is left over after spending.
446
The problem is that spending can expand to fill the available money.
447
If you have a little extra, you find something to do with it.
448
If you get a raise, your lifestyle gradually becomes more expensive.
449
If you receive a bonus, you start imagining what you could buy.
450
And before you know it, the money you thought would help you get ahead has already been spent.
451
A different approach is to give your money a purpose before you spend it.
452
When your paycheck arrives, decide what portion is going toward bills, what portion is going toward savings, what portion is going toward debt repayment,
453
and what portion is available for enjoyment.
454
The amounts will depend on your income and circumstances.
455
The principle is what matters.
456
Don't make your savings compete with every purchase you might want to make throughout the month.
457
Give your savings a role in your financial life before the spending begins.
458
And here's something that makes this approach more sustainable.
459
Include money for enjoyment.
460
Yes, really.
461
If your budget leaves no room for the things you genuinely like, it may become difficult to follow.
462
You might save aggressively for a few weeks, then feel deprived, then spend much more than you intended.
463
A more realistic approach is to build a financial plan that includes both your future and your present.
464
You can check out the Budget Blueprint video for an elaborate and flexible budget plan.
465
You don't have to choose between enjoying your life today and building a better life tomorrow.
466
You can make room for both.
467
The goal is to spend intentionally, not to spend as little as humanly possible.
468
Strategy 3.
469
Make your money harder to spend accidentally.
470
Remember what we discussed earlier about digital payments?
471
When spending becomes effortless, it can also become automatic.
472
So one way to change your spending habits is to introduce a little friction.
473
Not enough to make necessary purchases difficult, just enough to make unnecessary purchases less automatic.
474
For example, remove your saved payment details from shopping websites.
475
If buying something requires you to get your card and enter the information, you'll have an extra moment to think.
476
Turn off promotional shopping notifications.
477
Unsubscribe from emails that constantly advertise sales.
478
Remove shopping apps from your home screen.
479
And if you tend to shop when you're tired at night,
480
consider making a personal rule that you don't make non -essential purchases after a certain time.
481
These are small changes, but they alter the environment in which your decisions happen.
482
Instead of relying on yourself to resist every temptation, you're making the temptation less convenient.
483
And that matters, because your environment can influence your behavior long before you consciously decide what to do.
484
You don't need to prove that you can resist every advertisement.
485
You can simply choose not to expose yourself to so many of them.
486
You don't need to demonstrate that you can ignore every sale.
487
You can stop receiving notifications about sales you weren't interested in.
488
The point is to make the behavior you want easier and the behavior you want to reduce a little less convenient.
489
And that brings us to something even more powerful.
490
Because the next strategy isn't about making spending harder.
491
It's about making your priorities more visible.
492
Strategy four, connect every purchase to something you actually value.
493
Let's say you're considering buying a new television.
494
Your current television works perfectly well, but the new one has a bigger screen, better features, and a really attractive price.
495
You start thinking about how much you would enjoy it.
496
And then you ask yourself, what else could this money do for me?
497
Maybe it could help you build an emergency fund.
498
Maybe it could contribute to a trip you've been planning.
499
Maybe it could help you pay down a balance that's been bothering you.
500
Or maybe you decide that the television is genuinely worth it.
501
That's fine.
502
The point is to compare the purchase with your own priorities.
503
Not with someone else's lifestyle.
504
Not with the price of the item last week.
505
Not with the feeling of excitement you experienced when you first saw it.
506
With what matters to you.
507
Because money is a limited resource.
508
And the more clearly you understand what you want your money to accomplish,
509
the easier it becomes to recognize when a purchase supports your goals and when it pulls you away from them.
510
Here's a practical exercise.
511
Write down three things you want your money to help you achieve over the next year.
512
Keep them specific.
513
Maybe you want to build a $2 ,000 emergency fund.
514
Maybe you want to pay off a credit card.
515
Maybe you want to save for a vacation without borrowing money.
516
Whatever your goals are, make them visible.
517
Then, when you're considering a meaningful purchase, take a moment to look at those goals.
518
Ask yourself, does this purchase move me toward the life I'm trying to build, or does it move me away from it?
519
There isn't always a right or wrong answer.
520
You can spend money on something enjoyable and still be making a good decision.
521
But when you know what matters to you, you have a stronger basis for making that decision.
522
You're no longer just choosing between buying something and not buying something.
523
You're choosing between different ways of using your money.
524
And that can change the entire experience of spending.
525
Strategy 5.
526
Track the reason, not just the amount.
527
This is probably the most overlooked strategy.
528
Most people who track their spending focus on the numbers.
529
They record what they bought, they record how much it cost, and at the end of the month, they look at the totals.
530
That's useful.
531
But if you want to understand your spending habits, there's another piece of information worth tracking.
532
The reason behind the purchase.
533
For the next two weeks, whenever you make an unplanned purchase, write down three things.
534
What did you buy?
535
How much did it cost?
536
And what was happening when you decided to buy it?
537
Were you having a rough day?
538
Were you just scrolling through your phone when something caught your eye?
539
Or did you see a deal and convince yourself you couldn't pass it up?
540
You don't have to remember every detail.
541
Just think about what was going on in that moment.
542
Because sometimes, the reason you bought something has very little to do with the thing you actually bought.
543
Don't write a long explanation.
544
Just a few words.
545
At the end of two weeks, look for patterns.
546
You might discover that most of your unplanned spending happens late at night
547
or that you tend to overspend when you're with a particular group of friends
548
or that you're especially vulnerable to sales when you're already looking for something to buy.
549
Maybe you notice that you frequently purchase things connected to goals you haven't started working on.
550
These patterns can tell you more than the total amount you spent because now you have something specific to change.
551
If you tend to shop late at night, you can introduce a nighttime purchase rule.
552
If you overspend around friends, you can plan a reasonable amount for social activities.
553
If sales trigger you, you can unsubscribe from promotional emails.
554
If you repeatedly buy things for goals you never pursue, you can start focusing on the behavior before purchasing more equipment.
555
The important thing is that you're no longer treating your spending as a mysterious problem.
556
You're observing it.
557
And when you can observe a pattern, you can begin to change it.
558
What your spending habits are really telling you.
559
Now, I want to bring everything together, because after all this discussion about shopping, emotional spending, credit cards, discounts,
560
and social pressure, there's a bigger question underneath it all.
561
So what can your spending habits actually tell you?
562
Think about the things you tend to spend money on.
563
Maybe you don't mind paying a little extra to save yourself time.
564
Or maybe you keep buying things that make you feel like you're getting closer to the person you want to be.
565
And sometimes, you might be spending simply because you've had a long week and want something to look forward to.
566
None of that is necessarily a problem.
567
But if you look closely at where your money goes, you might notice that your spending doesn't always match what you say matters to you.
568
And that's worth paying attention to.
569
Because once you understand what's driving your spending, you can start making decisions that actually reflect the life you want.
570
That's not realistic.
571
You will buy things you don't need.
572
You will occasionally make a purchase you regret.
573
You will sometimes choose enjoyment over saving.
574
And that's part of being human.
575
What matters is whether those decisions are becoming a pattern that keeps you from the financial life you want.
576
If you find yourself spending more than you intended, don't immediately label yourself irresponsible.
577
Instead, look at the circumstances.
578
What triggered the purchase?
579
What were you hoping to feel?
580
What made the purchase seem reasonable?
581
What happened after you bought it?
582
And what could you change next time?
583
Because your spending habits are not fixed personality traits.
584
They're behaviors.
585
And behaviors can be examined, understood, and changed.
586
The same person who once bought things automatically can learn to pause.
587
The same person who once spent money to relieve stress can learn other ways to deal with stress.
588
The same person who once felt pressured to keep up with everyone else can begin defining success on their own terms.
589
It doesn't happen overnight, but it starts with paying attention.
590
And here's something I think is worth remembering.
591
Money isn't valuable simply because you keep it.
592
Money is valuable because of what it allows you to do.
593
Think about what having money can actually mean in your life.
594
It might mean not having to panic when an unexpected bill shows up.
595
It might mean being able to help your family when they need you.
596
Or having the freedom to walk away from a job that's making you miserable.
597
It could mean finally taking that trip you've been putting off for years.
598
And sure, sometimes it just means buying something you really like and enjoying it.
599
There's nothing wrong with that.
600
Because money isn't just about the things you own.
601
It's also about the choices you get to make, the worries you don't have to carry, and the kind of life you're able to build.
602
The problem isn't spending money.
603
The problem is spending money in ways that don't give you the life you thought you were buying.
604
So the next time you're about to make a purchase, take a moment.
605
Look beyond the product, the discount, and look beyond the excitement of the moment.
606
And ask yourself one simple question.
607
Is this something I genuinely want?
608
Or is this something I'm hoping will make me feel different?
609
Sometimes, the answer will be that you genuinely want it.
610
And you can buy it with confidence.
611
Other times, you'll realize that what you really need is something money can't provide.
612
And recognizing that can be worth far more than the purchase itself.
613
The money you spend is a reflection of what you believe.
614
Here's something I'd love for you to think about.
615
Imagine looking back at your spending one year from now.
616
Not just the amount you saved.
617
Not just the amount you earned.
618
But the decisions you made along the way.
619
The things you bought because they genuinely mattered to you.
620
The experiences you chose because they made your life better.
621
The purchases you walked away from because you realized you didn't really want them.
622
And the money you kept because it was helping you build something important.
623
What would you want that year to look like?
624
Because every purchase is a small decision about what matters to you in that moment.
625
And over time, those small decisions can shape your financial life.
626
You don't need to become perfect with money.
627
You don't need to stop enjoying shopping.
628
You don't need to feel guilty every time you spend a dollar.
629
You just need to become a little more aware of the decisions you're making.
630
Because once you understand why you spend, you can begin choosing how you spend.
631
And that is where financial control really begins.
632
So here's my question for you.
633
When you make an unplanned purchase, what usually drives it?
634
Is it the excitement of finding a great deal?
635
Is it stress?
636
Is it the desire to keep up with others?
637
Or is it simply the feeling of wanting something new?
638
Tell me in the comments.
639
I'd genuinely love to know which of these patterns you recognize in yourself.
640
And if this video helped you understand your relationship with money a little better, share it with someone who might need it.
641
Because sometimes, the most important financial lesson isn't about earning more money.
642
It's about understanding why we do what we do with the money we already have.
643
Thank you for spending your time with Simple Ways of Life.
644
Subscribe for more practical insights into money, psychology, and the small decisions that shape our lives.
645
Until next time, keep learning, keep growing, and keep it simple.

Download App

Everything you need to speak fluently

AI PronunciationScore every sentence
IPA PracticeMaster every sound
VocabularyBuild your word bank
Vocab GameLearn while playing

Same Channel

FOR YOU

Recommend Video

Vocabulary and speaking notes for this lesson

This speaking lesson is built on the video “The Psychology Behind Your Spending Habits”. The speaker keeps coming back to these words: purchase, spending, decision, buying. This video has 645 sentences and 6575 words to shadow. The speech runs for 35:21. The speaker talks fast, about 186 words per minute, so expect linked and reduced sounds. 88% of the words are among the 3,000 most common in English, so the vocabulary is easy to follow.

Key vocabulary in this video

15 words from the video worth learning, with pronunciation and meaning:

WordPronunciationMeaning
habit noun/ˈhæb.ɪt/An action performed on a regular basis.
discount noun/ˈdɪskaʊnt/A reduction in price.
genuinely adverb/ˈd͡ʒɛn.ju.ɪn.li/In a genuine manner; truthfully, truly.
compare verb/kəmˈpɛɚ/To assess the similarities and differences between two or more things [“to compare X with Y”]. Having made the comparison of X with Y, one might have found it…
arrive verb/əˈɹaɪv/To reach; to get to a certain place.
reward noun/ɹɪˈwɔɹd/Something of value given in return for an act.
excitement noun/ɪkˈsaɪtmənt/The state of being excited (emotionally aroused).
consequence noun/ˈkɑn.sɪ.kwəns/An effect; something that follows a cause as a result.
practical adjective/ˈpɹæk.tɪ.kəl/Relating to, or based on, practice or action rather than theory or hypothesis.
vacation noun/veɪˈkeɪ.ʃən/An extended trip or journey away from home for rest or pleasure.
automatic adjective/ˌɔː.təˈmæt.ɪk/Capable of operating without external control or intervention.
priority noun/pɹaɪˈɒɹɪti/An item's relative importance.
visible adjective/ˈvɪzɪb(ə)l/Able to be seen.
jacket noun/ˈd͡ʒæk.ɪt/A piece of clothing worn on the upper body outside a shirt or blouse, often waist length to thigh length.
psychological adjective/ˌsaɪ.kəˈlɑː.d͡ʒɪ.kl̩/Of or pertaining to psychology.

Phrasal verbs you will hear

WordMeaning
give up verbTo surrender (someone or something); to inform on (someone).
write down verbTo produce or set (something) down in writing; to record something.
hand over verbTo relinquish control or possession of something to someone.
keep up with verbTo manage to remain beside or just behind someone or something that is moving away from one.
look forward to verbTo anticipate, expect, or wait for, especially with a feeling of approval or pleasure; to be excited or eager to.
miss out verbTo miss an experience or lose an opportunity, etc. that should not be missed.
pay down verbTo partially repay (a loan or, metonymically, the thing financed by it).
pay off verbTo bribe, especially to deter oversight.

Sentences worth repeating

Short, complete lines from the video that you can reuse in everyday conversation:

  • What were you actually looking forward to?
  • What am I feeling right now?
  • Are you looking for a reward?
  • Are you trying to feel more in control?
  • Are you simply looking for something interesting to do?

Grammar in this video

The structures the speaker uses most, with the exact words from the video:

StructureIn the video
Present perfect continuous have/has been + -ing — an action that started earlier and is still going onyou've been thinking · you've been dealing · you've been carrying
Conditional sentences if + clause, will/would + verb — a condition and its resultIf this item were not discounted, would I
Present perfect have/has + past participle — a past action that still matters nowYou've had · haven't really had · you've received
Passive voice be + past participle — the focus is on what happens, not who does itcan be purchased · is placed · been solved

Pronunciation to watch

The speaker uses 188 contractions and reduced forms, such as you're, don't, you've. Say them the short way, as you hear them.

  • The “sh” and “zh” sounds: vacation /veɪˈkeɪ.ʃən/, emotion /ɪˈməʊ.ʃən/, transaction /tɹænˈzækʃən/, promotional /pɹəˈmoʊʃənəl/, regulation /ˌɹɛɡjʊˈleɪʃən/
  • Long words — get the stress right: genuinely /ˈd͡ʒɛn.ju.ɪn.li/, automatic /ˌɔː.təˈmæt.ɪk/, priority /pɹaɪˈɒɹɪti/, psychological /ˌsaɪ.kəˈlɑː.d͡ʒɪ.kl̩/, psychology /saɪˈkɑ.lə.d͡ʒi/

How to practise with this video

  1. Listen to the whole video once without speaking and note the words you do not know.
  2. Start at 0.75× speed, shadow it sentence by sentence, then go back to normal speed once it feels easy.
  3. Record yourself and compare with the original, paying attention to words like habit, discount, genuinely.

What is the Shadowing Technique?

Shadowing is a science-backed language learning technique originally developed for professional interpreter training and popularized by polyglot Dr. Alexander Arguelles. The method is simple but powerful: you listen to native English audio and immediately repeat it out loud — like a shadow following the speaker with just a 1–2 second delay. Unlike passive listening or grammar drills, shadowing forces your brain and mouth muscles to simultaneously process and reproduce real speech patterns. Research shows it significantly improves pronunciation accuracy, intonation, rhythm, connected speech, listening comprehension, and speaking fluency — making it one of the most effective methods for IELTS Speaking preparation and real-world English communication.

Shadowing technique: read the full step-by-step guide →