シャドーイング練習: The INCOME STATEMENT Explained (Profit & Loss / P&L) - 動画で英語スピーキングを学ぶ

練習モードを選ぶ

各モードは全画面の練習ルームで開きます。

142 文
文が短すぎたり長すぎる場合は、Editをタップして調整してください。
1
In this video you'll learn what an income statement is.
2
I'll show you what it looks like and how you can use it to measure a business's financial performance.
3
Hey there, welcome back to Accounting Stuff.
4
I'm James and in today's video we're going to cover the income statement.
5
Also known as the profit and loss statement or the P&L for short.
6
This is one of the three major financial statements in accounting along with the balance sheet and the cash flow statement.
7
Collectively these reports give us an impression of a business's financial health so it's important that we understand how they work.
8
I've already made videos covering the balance sheet and the cash flow statement
9
which you can find linked up here and down below in the description
10
but up until now I haven't posted a video yet on the income statement
11
and I've received a lot of requests from you guys to cover this topic
12
so thanks for all these particularly from one subscriber so Niloy
13
if you're watching this video goes out to you good luck in your exam hope you crush it.
14
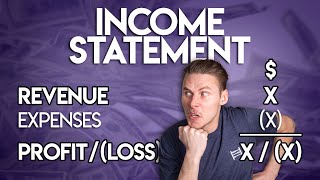
An income statement is the summary of a business's revenues and expenses over a period of time.
15
In its basic form an income statement looks like this it's a summary of a business's revenues
16
and expenses over a period of time.
17
When we take our total revenue and and subtract our expenses from it then we work out our profit or our loss.
18
We make a profit when our revenues exceed our expenses
19
and on the flip side we make a loss when our expenses are more than the income we've earned.
20
This is why the income statement is also known as the profit and loss statement or the P&L for short.
21
It lays out a roadmap for how we ended up here at the bottom line our profit or loss.
22
The income statement always covers a period of time
23
which could be anything that we want it to be but typically we run it for a month, a quarter or a full year.
24
Here's a helpful analogy that I read in this book The Accounting Game which I recommend reading if you're new to accounting.
25
You can find my review of it up here.
26
Anyway back to it.
27
If a balance sheet shows us a snapshot of a business's assets, liabilities and equity at a single point in time,
28
then you can think of it as a photograph or a still frame taken from a video.
29
Whereas the income statement covers a period of time.
30
It's like watching a clip of that video.
31
It has a beginning and it has an end.
32
And if we look at it carefully and analyze it, then it can tell us a story.
33
But more on that later.
34
Let's take a closer look at our income statement.
35
Revenues, less expenses, make us a profit or a loss.
36
The problem with this layout is that it doesn't give us much detail.
37
It would be much better if we made things a little more descriptive.
38
For instance, revenue.
39
There are many different types of revenue.
40
If we were running a business that sells physical products then we might want to call this product sales instead.
41
Or if we provide services we could call this our services rendered.
42
This extra detail helps the readers of the income statement better understand what they're looking at.
43
Clarity is the aim of the game here.
44
The same goes for expenses.
45
Businesses typically incur many different types of expense but broadly speaking these can be broken down into two categories.
46
Our direct costs of doing business and our indirect costs of running the business.
47
Our direct costs of doing business are the costs
48
which we can directly trace through to the products we've sold or the services that we've provided.
49
For a business that provides services we might call this our cost of services
50
and if we sell physical goods then we could call this our cost of sales or our cost of goods sold.
51
Direct costs like these are variable costs which increase in direct proportion to the sales that we've made.
52
If you are running a retail
53
or a wholesale business then these would include things like the original purchase price of the product
54
that you're reselling or
55
if you've run a manufacturing business then this would include the cost of your raw materials
56
or the direct labor cost that went into producing your product.
57
As we make more sales we incur more of these direct costs.
58
Cost of goods sold can be a bit of a tricky concept to understand at first.
59
It ties in very closely with inventory in the balance sheet.
60
If you'd like to see me make a video explaining how all of
61
that works then let me know down below in the comments
62
and if you haven't already remember to hit that subscribe button
63
so you don't miss out on all of the other accounting tutorials that we have coming out very soon.
64
Back to the income statement.
65
When we take our revenue and deduct our direct costs of doing business we get to our gross profit.
66
If you're new to accounting then you'll soon discover that we have many different types of profit.
67
Our gross profit is a really useful tool that allows us to measure the efficiency of our production and sales process.
68
I'll show you how that works in a minute.
69
But first let's jump back to indirect costs.
70
These are the costs of running a business
71
which can't directly be traced back to the production of goods or the provision of services.
72
We sometimes call these overheads.
73
Overheads can include fixed costs like rent, employee salaries, insurance costs, admin expenses,
74
legal costs, accounting costs, marketing costs, depreciation and amortization.
75
Whoa, there's a lot of them.
76
Fixed costs like these tend to remain the same.
77
They bear no correlation at all to the sales that your business has made.
78
However, not all overheads are fixed.
79
Variable overheads can loosely correlate with a business's sales, although they can't be directly traced back to the production of goods or the provision of services.
80
These include things like advertising costs, which can indirectly drive sales and sales commissions.
81
Utility costs could also be considered a variable overhead in a manufacturing business because these can increase as we ramp up production.
82
When we deduct our indirect costs of doing business from our gross profit, we come to our operating profit.
83
Operating profit measures the net income that we generated from operations.
84
This is the residual amount that's left over after deducting all of our direct and indirect costs of doing business.
85
So this is our basic income statement.
86
But how does it help us measure a business's financial health?
87
It does that by giving us a means to compare our financial performance against comparative accounting periods.
88
A comparative period is a different period of time.
89
It can be whatever we want it to be.
90
We could compare a current month income statement against last month's income statement or this year versus last year.
91
When we use comparative periods we can calculate the change
92
or movement across each line item down the profit and loss statement
93
and as accountants it's our job to support these movements with a narrative which explains all of the differences.
94
Let's throw in some numbers into an imaginary company and I'll show you what I mean.
95
We'll compare the movements in our P&L year on year.
96
This is going to be for a medium-sized business so we can quote our numbers in thousands of dollars.
97
What have we got here?
98
Our imaginary company has made sales of $110,000 which is up $10,000 from what we made in the prior year.
99
Our cost of goods sold have also increased by $10,000 from $30,000 to $40,000.
100
That's left us with a gross profit of $70,000 which has remained unchanged.
101
Our overheads are fixed at $45,000 which gives us an operating profit of $25,000 in each period.
102
What can we learn from all of this?
103
Well our sales have increased by $10,000 but our gross profit has remained exactly the same.
104
How can that be?
105
A useful metric that we can use to analyze this is gross profit margin.
106
We can calculate our gross profit margin by taking our total product sales
107
and deducting our costs of goods sold and then dividing the whole lot by our product sales.
108
This measures how efficiently we've been producing and selling our imaginary product.
109
In this case our gross profit margin in the current year is around 64%
110
which is actually down from last year's gross profit margin of 70%.
111
How's that possible?
112
Well one of two things could be happening here.
113
Our sales could be shrinking or our costs could be rising.
114
We could be selling more products but at a discount or the cost of our raw materials could be rising.
115
These are the questions that we need to be asking ourselves as accountants, investors or small business owners.
116
We can compare metrics like the gross profit margin across comparative
117
periods to help us identify what questions we should be asking and then Then, that's when the work begins.
118
We need to find out the answers and use them to build a narrative that explains what's going on.
119
Gross profit margin is just one of many business metrics that we can use to analyse the income statement.
120
If you'd like to see me make videos on the others, let me know.
121
Now, this is still quite a basic income statement.
122
In reality there are other indirect costs of doing business which we might need to include as well.
123
Things like interest expenses and tax.
124
These tend to slot in below operating profit because they aren't considered to fall within the normal cost of operations.
125
This is why operating profit is also known as EBIT or earnings before interest and tax.
126
When we deduct our interest
127
and tax from our operating profit we calculate our net profit the bottom line
128
because it's at the bottom of the profit and loss statement.
129
So you can see that there are many different types of profit and loss to consider in accounting.
130
We start off with our revenue and we deduct our direct costs of doing business to come to our gross profit, our top line profit.
131
Below this we take out the indirect costs of running our business to find our operating profit, our EBIT, our earnings before interest and tax.
132
And when we remove interest and tax we calculate our net profit, the bottom line.
133
these different types of profit help us measure performance over a period of time.
134
The main goal of most businesses is to maximize their profits
135
so it's important to be clear on what that means and to be aware of the differences between gross profit,
136
operating profit and net profit which can each tell us a different part of the story.
137
Like I mentioned earlier the income statement is just one of
138
the three main financial statements along with the balance sheet and the cash flow statement.
139
I've made videos covering both of these already which you can find here and here.
140
If you found this one useful give it a like or better yet share it with a friend, why not?
141
Don't forget to subscribe for more accounting tutorials.
142
I'll see you around.

アプリをダウンロード

流暢に話すために必要なすべて

AI発音採点文ごとに採点
IPA練習すべての音をマスター
単語学習自分の単語帳を作る
単語ゲーム遊びながら覚える

同じチャンネル

FOR YOU

おすすめ動画

このレッスンの語彙とスピーキングのポイント

このC1レベルのスピーキングレッスンは、動画「The INCOME STATEMENT Explained」を教材にしています。 繰り返し出てくる語は次のとおりです:profit, cost, statement, income, sales。 この動画には、シャドーイング用の文が142文、単語が1913語あります。 音声の長さは11:20です。 話す速さは1分あたり約169語で、日常会話に近い自然なペースです。 単語の86%は英語の頻出3,000語に含まれます。残りは練習の前に確認しておきましょう。

この動画の重要語彙

動画の中で特に難しい単語15語を、発音と意味つきで紹介します。

単語発音意味
deduct 動詞/dɪˈdʌkt/差し引く, 引く
overhead 名詞/ˈəʊvəˌhɛd/オーバーヘッド, 間接費
calculate 動詞/ˈkælkjʊleɪt/計算する
imaginary 形容詞/ɪˈmæd͡ʒɪˌn(ɛ)ɹi/架空の, 幻想的な
accountant 名詞/əˈkaʊn.tənt/会計士
tutorial 名詞/ˌtjuːˈtɔːɹɪəl/学習用, チュートリアル
analyze 動詞/ˈæn.əˌlaɪz/分析する
subscribe 動詞/səbˈskɹaɪb/購読する
amortization 名詞/ˌæmɚtəˈzeɪʃən/償却
depreciation 名詞/dɪˌpɹiːʃɪˈeɪʃən/減価償却
resell 動詞/ɹiːˈsɛl/転売する
snapshot 名詞/ˈsnæpʃɒt/スナップショット
subtract 動詞/səbˈtɹækt/引く, 減らす
subscriber 名詞/səbˈskɹaɪbɚ/購読者, 加入者
descriptive 形容詞/dəˈskɹɪptɪv/限定用法の

動画に出てくる句動詞

単語発音意味
come out 動詞/ˌkʌm ˈaʊt/出る
find out 動詞見出す, 調べる
take out 動詞取り出す

繰り返し練習したい文

動画に出てくる短く完結した文です。日常会話でそのまま使えます。

  • Let's take a closer look at our income statement.
  • I'll show you how that works in a minute.
  • What have we got here?
  • What can we learn from all of this?

この動画の文法

話し手がよく使っている文型を、動画の実際の表現とともに紹介します。

文型動画での表現
条件文 if + 節, will/would + 動詞 — 条件とその結果If you're new to accounting then you'll soon
現在完了形 have/has + 過去分詞 — 過去の出来事が今も関係しているI've already made · haven't posted · I've received
受動態 be + 過去分詞 — 誰がするかより、何が起きるかに焦点を当てるis also known · can be broken · be traced
関係詞節 who / which + 節 — 人や物について情報を加えるcosts, which can · profit which can

注意したい発音

話し手はwe've, I'll, you'reなど、短縮形や弱形を33回使っています。聞こえたとおりの短い形で発音しましょう。

  • 「sh」と「zh」の音: amortization /ˌæmɚtəˈzeɪʃən/, depreciation /dɪˌpɹiːʃɪˈeɪʃən/, snapshot /ˈsnæpʃɒt/, correlation /ˌkɔɹ.əˈleɪ.ʃən/
  • 長い単語(アクセントの位置に注意): comparative /kəmˈpæɹətɪv/, imaginary /ɪˈmæd͡ʒɪˌn(ɛ)ɹi/, amortization /ˌæmɚtəˈzeɪʃən/, depreciation /dɪˌpɹiːʃɪˈeɪʃən/, residual /ɹɪˈzɪd͡ʒ.u.əl/

日本語話者が苦手な音:

  • /r/ と /l/ の区別 — /l/ は舌先を歯茎につけ、/r/ はどこにもつけない: tutorial /ˌtjuːˈtɔːɹɪəl/, correlate /ˈkɔɹəleɪt/, resell /ɹiːˈsɛl/, residual /ɹɪˈzɪd͡ʒ.u.əl/, indirectly /ˌɪn.dɪˈɹɛk(t).li/
  • /v/ — /b/ にならないように、上の歯を下唇に当てる: overhead /ˈəʊvəˌhɛd/, comparative /kəmˈpæɹətɪv/, descriptive /dəˈskɹɪptɪv/, investor /ɪnˈvɛs.tə(ɹ)/
  • 子音の連続 — 間に母音を入れない: deduct /dɪˈdʌkt/, indirect /ˌɪn.daɪˈɹɛkt/, calculate /ˈkælkjʊleɪt/, accountant /əˈkaʊn.tənt/, tutorial /ˌtjuːˈtɔːɹɪəl/

この動画での練習方法

  1. まず声を出さずに動画を最後まで聞き、知らない単語をメモします。
  2. まず0.75倍速で一文ずつシャドーイングし、慣れてきたら通常の速度に戻します。
  3. 自分の声を録音して元の音声と比べます。deduct, overhead, calculateなどの単語に特に注意しましょう。

シャドーイングとは?英語上達に効果的な理由

シャドーイング(Shadowing)は、もともとプロの通訳者養成プログラムで開発された言語学習法で、多言語習得者として知られるDr. Alexander Arguelles によって広く普及されました。方法はシンプルですが非常に効果的:ネイティブスピーカーの英語を聞きながら、1〜2秒の遅延で声に出してすぐに繰り返す——まるで「影(shadow)」のように話者を追いかけます。文法ドリルや受動的なリスニングと異なり、シャドーイングは脳と口の筋肉が同時にリアルタイムで英語を処理・再現することを強制します。研究により、発音精度、抑揚、リズム、連音、リスニング力、そして会話の流暢さが大幅に向上することが確認されています。IELTSスピーキング対策や自然な英語コミュニケーションを目指す方に特におすすめです。

シャドーイングのやり方: ステップ別の完全ガイドを読む →