쉐도잉 연습: The INCOME STATEMENT Explained (Profit & Loss / P&L) - 영상으로 영어 말하기 배우기

연습 모드 선택

각 모드는 전체 화면 연습실로 열립니다.

142 문장
문장이 너무 짧거나 길면 Edit를 눌러 조정하세요.
1
In this video you'll learn what an income statement is.
2
I'll show you what it looks like and how you can use it to measure a business's financial performance.
3
Hey there, welcome back to Accounting Stuff.
4
I'm James and in today's video we're going to cover the income statement.
5
Also known as the profit and loss statement or the P&L for short.
6
This is one of the three major financial statements in accounting along with the balance sheet and the cash flow statement.
7
Collectively these reports give us an impression of a business's financial health so it's important that we understand how they work.
8
I've already made videos covering the balance sheet and the cash flow statement
9
which you can find linked up here and down below in the description
10
but up until now I haven't posted a video yet on the income statement
11
and I've received a lot of requests from you guys to cover this topic
12
so thanks for all these particularly from one subscriber so Niloy
13
if you're watching this video goes out to you good luck in your exam hope you crush it.
14
An income statement is the summary of a business's revenues and expenses over a period of time.
15
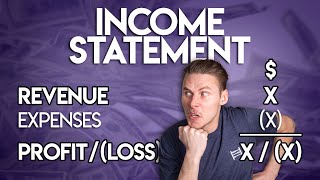
In its basic form an income statement looks like this it's a summary of a business's revenues
16
and expenses over a period of time.
17
When we take our total revenue and and subtract our expenses from it then we work out our profit or our loss.
18
We make a profit when our revenues exceed our expenses
19
and on the flip side we make a loss when our expenses are more than the income we've earned.
20
This is why the income statement is also known as the profit and loss statement or the P&L for short.
21
It lays out a roadmap for how we ended up here at the bottom line our profit or loss.
22
The income statement always covers a period of time
23
which could be anything that we want it to be but typically we run it for a month, a quarter or a full year.
24
Here's a helpful analogy that I read in this book The Accounting Game which I recommend reading if you're new to accounting.
25
You can find my review of it up here.
26
Anyway back to it.
27
If a balance sheet shows us a snapshot of a business's assets, liabilities and equity at a single point in time,
28
then you can think of it as a photograph or a still frame taken from a video.
29
Whereas the income statement covers a period of time.
30
It's like watching a clip of that video.
31
It has a beginning and it has an end.
32
And if we look at it carefully and analyze it, then it can tell us a story.
33
But more on that later.
34
Let's take a closer look at our income statement.
35
Revenues, less expenses, make us a profit or a loss.
36
The problem with this layout is that it doesn't give us much detail.
37
It would be much better if we made things a little more descriptive.
38
For instance, revenue.
39
There are many different types of revenue.
40
If we were running a business that sells physical products then we might want to call this product sales instead.
41
Or if we provide services we could call this our services rendered.
42
This extra detail helps the readers of the income statement better understand what they're looking at.
43
Clarity is the aim of the game here.
44
The same goes for expenses.
45
Businesses typically incur many different types of expense but broadly speaking these can be broken down into two categories.
46
Our direct costs of doing business and our indirect costs of running the business.
47
Our direct costs of doing business are the costs
48
which we can directly trace through to the products we've sold or the services that we've provided.
49
For a business that provides services we might call this our cost of services
50
and if we sell physical goods then we could call this our cost of sales or our cost of goods sold.
51
Direct costs like these are variable costs which increase in direct proportion to the sales that we've made.
52
If you are running a retail
53
or a wholesale business then these would include things like the original purchase price of the product
54
that you're reselling or
55
if you've run a manufacturing business then this would include the cost of your raw materials
56
or the direct labor cost that went into producing your product.
57
As we make more sales we incur more of these direct costs.
58
Cost of goods sold can be a bit of a tricky concept to understand at first.
59
It ties in very closely with inventory in the balance sheet.
60
If you'd like to see me make a video explaining how all of
61
that works then let me know down below in the comments
62
and if you haven't already remember to hit that subscribe button
63
so you don't miss out on all of the other accounting tutorials that we have coming out very soon.
64
Back to the income statement.
65
When we take our revenue and deduct our direct costs of doing business we get to our gross profit.
66
If you're new to accounting then you'll soon discover that we have many different types of profit.
67
Our gross profit is a really useful tool that allows us to measure the efficiency of our production and sales process.
68
I'll show you how that works in a minute.
69
But first let's jump back to indirect costs.
70
These are the costs of running a business
71
which can't directly be traced back to the production of goods or the provision of services.
72
We sometimes call these overheads.
73
Overheads can include fixed costs like rent, employee salaries, insurance costs, admin expenses,
74
legal costs, accounting costs, marketing costs, depreciation and amortization.
75
Whoa, there's a lot of them.
76
Fixed costs like these tend to remain the same.
77
They bear no correlation at all to the sales that your business has made.
78
However, not all overheads are fixed.
79
Variable overheads can loosely correlate with a business's sales, although they can't be directly traced back to the production of goods or the provision of services.
80
These include things like advertising costs, which can indirectly drive sales and sales commissions.
81
Utility costs could also be considered a variable overhead in a manufacturing business because these can increase as we ramp up production.
82
When we deduct our indirect costs of doing business from our gross profit, we come to our operating profit.
83
Operating profit measures the net income that we generated from operations.
84
This is the residual amount that's left over after deducting all of our direct and indirect costs of doing business.
85
So this is our basic income statement.
86
But how does it help us measure a business's financial health?
87
It does that by giving us a means to compare our financial performance against comparative accounting periods.
88
A comparative period is a different period of time.
89
It can be whatever we want it to be.
90
We could compare a current month income statement against last month's income statement or this year versus last year.
91
When we use comparative periods we can calculate the change
92
or movement across each line item down the profit and loss statement
93
and as accountants it's our job to support these movements with a narrative which explains all of the differences.
94
Let's throw in some numbers into an imaginary company and I'll show you what I mean.
95
We'll compare the movements in our P&L year on year.
96
This is going to be for a medium-sized business so we can quote our numbers in thousands of dollars.
97
What have we got here?
98
Our imaginary company has made sales of $110,000 which is up $10,000 from what we made in the prior year.
99
Our cost of goods sold have also increased by $10,000 from $30,000 to $40,000.
100
That's left us with a gross profit of $70,000 which has remained unchanged.
101
Our overheads are fixed at $45,000 which gives us an operating profit of $25,000 in each period.
102
What can we learn from all of this?
103
Well our sales have increased by $10,000 but our gross profit has remained exactly the same.
104
How can that be?
105
A useful metric that we can use to analyze this is gross profit margin.
106
We can calculate our gross profit margin by taking our total product sales
107
and deducting our costs of goods sold and then dividing the whole lot by our product sales.
108
This measures how efficiently we've been producing and selling our imaginary product.
109
In this case our gross profit margin in the current year is around 64%
110
which is actually down from last year's gross profit margin of 70%.
111
How's that possible?
112
Well one of two things could be happening here.
113
Our sales could be shrinking or our costs could be rising.
114
We could be selling more products but at a discount or the cost of our raw materials could be rising.
115
These are the questions that we need to be asking ourselves as accountants, investors or small business owners.
116
We can compare metrics like the gross profit margin across comparative
117
periods to help us identify what questions we should be asking and then Then, that's when the work begins.
118
We need to find out the answers and use them to build a narrative that explains what's going on.
119
Gross profit margin is just one of many business metrics that we can use to analyse the income statement.
120
If you'd like to see me make videos on the others, let me know.
121
Now, this is still quite a basic income statement.
122
In reality there are other indirect costs of doing business which we might need to include as well.
123
Things like interest expenses and tax.
124
These tend to slot in below operating profit because they aren't considered to fall within the normal cost of operations.
125
This is why operating profit is also known as EBIT or earnings before interest and tax.
126
When we deduct our interest
127
and tax from our operating profit we calculate our net profit the bottom line
128
because it's at the bottom of the profit and loss statement.
129
So you can see that there are many different types of profit and loss to consider in accounting.
130
We start off with our revenue and we deduct our direct costs of doing business to come to our gross profit, our top line profit.
131
Below this we take out the indirect costs of running our business to find our operating profit, our EBIT, our earnings before interest and tax.
132
And when we remove interest and tax we calculate our net profit, the bottom line.
133
these different types of profit help us measure performance over a period of time.
134
The main goal of most businesses is to maximize their profits
135
so it's important to be clear on what that means and to be aware of the differences between gross profit,
136
operating profit and net profit which can each tell us a different part of the story.
137
Like I mentioned earlier the income statement is just one of
138
the three main financial statements along with the balance sheet and the cash flow statement.
139
I've made videos covering both of these already which you can find here and here.
140
If you found this one useful give it a like or better yet share it with a friend, why not?
141
Don't forget to subscribe for more accounting tutorials.
142
I'll see you around.

앱 다운로드

유창하게 말하는 데 필요한 모든 것

AI 발음 평가문장마다 점수 확인
IPA 발음 연습모든 소리 마스터
단어 학습나만의 단어장 만들기
단어 게임놀면서 외우기

같은 채널

FOR YOU

추천 영상

이 레슨의 어휘와 말하기 포인트

이 C1 수준 말하기 레슨은 영상 “The INCOME STATEMENT Explained”을(를) 바탕으로 합니다. 가장 자주 반복되는 단어는 다음과 같습니다: profit, cost, statement, income, sales. 이 영상에는 섀도잉할 문장 142개와 단어 1913개가 있습니다. 말하는 구간의 길이는 11:20입니다. 화자는 분당 약 169단어로, 일상 대화에 가까운 자연스러운 속도로 말합니다. 단어의 86%가 영어에서 가장 많이 쓰이는 3,000단어에 속합니다. 나머지는 연습 전에 미리 확인해 두세요.

이 영상의 핵심 어휘

영상에서 가장 어려운 단어 15개를 발음, 뜻과 함께 정리했습니다.

단어발음뜻
calculate 동사/ˈkælkjʊleɪt/정산하다, 계산하다
imaginary 형용사/ɪˈmæd͡ʒɪˌn(ɛ)ɹi/환상적, 가상적
accountant 명사/əˈkaʊn.tənt/회계사
tutorial 명사/ˌtjuːˈtɔːɹɪəl/지도, 지침
analyze 동사/ˈæn.əˌlaɪz/분석하다
subscribe 동사/səbˈskɹaɪb/구독하다
amortization 명사/ˌæmɚtəˈzeɪʃən/상각
depreciation 명사/dɪˌpɹiːʃɪˈeɪʃən/감가상각
snapshot 명사/ˈsnæpʃɒt/스냅샷
subtract 동사/səbˈtɹækt/빼다
subscriber 명사/səbˈskɹaɪbɚ/구독자, 가입자
maximize 동사/ˈmæksəmaɪz/최대화(最大化)하다
analogy 명사/əˈnæləd͡ʒi/유추
render 동사/ˈɹɛn.dɚ/일어나게 하다, 하게하다
investor 명사/ɪnˈvɛs.tə(ɹ)/투자자

영상에 나오는 구동사

단어발음뜻
come out 동사/ˌkʌm ˈaʊt/나오다

따라 말해 볼 만한 문장

영상에 나오는 짧고 완결된 문장으로, 일상 대화에서 그대로 쓸 수 있습니다:

  • Let's take a closer look at our income statement.
  • I'll show you how that works in a minute.
  • What have we got here?
  • What can we learn from all of this?

이 영상의 문법

화자가 가장 많이 쓰는 문형을 영상 속 실제 표현과 함께 정리했습니다.

문형영상 속 표현
조건문 if + 절, will/would + 동사 — 조건과 그 결과If you're new to accounting then you'll soon
현재완료 have/has + 과거분사 — 과거의 일이 지금도 관련이 있을 때I've already made · haven't posted · I've received
수동태 be + 과거분사 — 누가 하는지보다 무슨 일이 일어나는지에 초점is also known · can be broken · be traced
관계절 who / which + 절 — 사람이나 사물에 대한 추가 정보costs, which can · profit which can

주의할 발음

화자는 we've, I'll, you're 같은 축약형과 약화된 형태를 33번 사용합니다. 들리는 대로 짧게 발음하세요.

  • “sh”와 “zh” 소리: amortization /ˌæmɚtəˈzeɪʃən/, depreciation /dɪˌpɹiːʃɪˈeɪʃən/, snapshot /ˈsnæpʃɒt/, correlation /ˌkɔɹ.əˈleɪ.ʃən/
  • 긴 단어 — 강세 위치에 주의: comparative /kəmˈpæɹətɪv/, imaginary /ɪˈmæd͡ʒɪˌn(ɛ)ɹi/, amortization /ˌæmɚtəˈzeɪʃən/, depreciation /dɪˌpɹiːʃɪˈeɪʃən/, residual /ɹɪˈzɪd͡ʒ.u.əl/

한국어 화자가 어려워하는 소리:

  • /v/ — ㅂ(/b/)과 구별하기: overhead /ˈəʊvəˌhɛd/, comparative /kəmˈpæɹətɪv/, descriptive /dəˈskɹɪptɪv/, investor /ɪnˈvɛs.tə(ɹ)/
  • /z/ — ㅈ이 아니라 성대를 울리는 /s/: analyze /ˈæn.əˌlaɪz/, amortization /ˌæmɚtəˈzeɪʃən/, residual /ɹɪˈzɪd͡ʒ.u.əl/, maximize /ˈmæksəmaɪz/
  • /r/과 /l/ 구별하기: tutorial /ˌtjuːˈtɔːɹɪəl/, correlate /ˈkɔɹəleɪt/, resell /ɹiːˈsɛl/, residual /ɹɪˈzɪd͡ʒ.u.əl/, indirectly /ˌɪn.dɪˈɹɛk(t).li/

이 영상으로 연습하는 방법

  1. 먼저 말하지 않고 영상을 끝까지 듣고 모르는 단어를 적어 둡니다.
  2. 0.75배속으로 한 문장씩 섀도잉을 시작하고, 익숙해지면 보통 속도로 돌아갑니다.
  3. 자신의 목소리를 녹음해 원본과 비교하고, calculate, imaginary, accountant 같은 단어에 특히 주의합니다.

쉐도잉이란? 영어 실력을 빠르게 키우는 과학적 방법

쉐도잉(Shadowing)은 원래 전문 통역사 훈련을 위해 개발된 언어 학습 기법으로, 다언어 학자인 Dr. Alexander Arguelles에 의해 대중화된 방법입니다. 핵심 원리는 간단하지만 매우 강력합니다: 원어민의 영어를 들으면서 1~2초의 짧은 지연으로 즉시 소리 내어 따라 말하는 것——마치 '그림자(shadow)'처럼 화자를 따라가는 것입니다. 문법 공부나 수동적인 청취와 달리, 쉐도잉은 뇌와 입 근육이 동시에 실시간으로 영어를 처리하고 재현하도록 훈련합니다. 연구에 따르면 이 방법은 발음 정확도, 억양, 리듬, 연음, 청취력, 말하기 유창성을 크게 향상시킵니다. IELTS 스피킹 준비와 자연스러운 영어 소통을 원하는 분들에게 특히 효과적입니다.

섀도잉 방법: 단계별 전체 가이드 읽기 →