ฝึกพูดภาษาอังกฤษด้วยเทคนิค Shadowing จากวิดีโอ: The INCOME STATEMENT Explained (Profit & Loss / P&L)

เลือกโหมดฝึก

แต่ละโหมดจะเปิดห้องฝึกแบบเต็มจอ

142 ประโยค
หากประโยคสั้นหรือยาวเกินไป กดที่ Edit เพื่อปรับแก้
1
In this video you'll learn what an income statement is.
2
I'll show you what it looks like and how you can use it to measure a business's financial performance.
3
Hey there, welcome back to Accounting Stuff.
4
I'm James and in today's video we're going to cover the income statement.
5
Also known as the profit and loss statement or the P&L for short.
6
This is one of the three major financial statements in accounting along with the balance sheet and the cash flow statement.
7
Collectively these reports give us an impression of a business's financial health so it's important that we understand how they work.
8
I've already made videos covering the balance sheet and the cash flow statement
9
which you can find linked up here and down below in the description
10
but up until now I haven't posted a video yet on the income statement
11
and I've received a lot of requests from you guys to cover this topic
12
so thanks for all these particularly from one subscriber so Niloy
13
if you're watching this video goes out to you good luck in your exam hope you crush it.
14
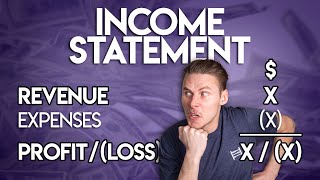
An income statement is the summary of a business's revenues and expenses over a period of time.
15
In its basic form an income statement looks like this it's a summary of a business's revenues
16
and expenses over a period of time.
17
When we take our total revenue and and subtract our expenses from it then we work out our profit or our loss.
18
We make a profit when our revenues exceed our expenses
19
and on the flip side we make a loss when our expenses are more than the income we've earned.
20
This is why the income statement is also known as the profit and loss statement or the P&L for short.
21
It lays out a roadmap for how we ended up here at the bottom line our profit or loss.
22
The income statement always covers a period of time
23
which could be anything that we want it to be but typically we run it for a month, a quarter or a full year.
24
Here's a helpful analogy that I read in this book The Accounting Game which I recommend reading if you're new to accounting.
25
You can find my review of it up here.
26
Anyway back to it.
27
If a balance sheet shows us a snapshot of a business's assets, liabilities and equity at a single point in time,
28
then you can think of it as a photograph or a still frame taken from a video.
29
Whereas the income statement covers a period of time.
30
It's like watching a clip of that video.
31
It has a beginning and it has an end.
32
And if we look at it carefully and analyze it, then it can tell us a story.
33
But more on that later.
34
Let's take a closer look at our income statement.
35
Revenues, less expenses, make us a profit or a loss.
36
The problem with this layout is that it doesn't give us much detail.
37
It would be much better if we made things a little more descriptive.
38
For instance, revenue.
39
There are many different types of revenue.
40
If we were running a business that sells physical products then we might want to call this product sales instead.
41
Or if we provide services we could call this our services rendered.
42
This extra detail helps the readers of the income statement better understand what they're looking at.
43
Clarity is the aim of the game here.
44
The same goes for expenses.
45
Businesses typically incur many different types of expense but broadly speaking these can be broken down into two categories.
46
Our direct costs of doing business and our indirect costs of running the business.
47
Our direct costs of doing business are the costs
48
which we can directly trace through to the products we've sold or the services that we've provided.
49
For a business that provides services we might call this our cost of services
50
and if we sell physical goods then we could call this our cost of sales or our cost of goods sold.
51
Direct costs like these are variable costs which increase in direct proportion to the sales that we've made.
52
If you are running a retail
53
or a wholesale business then these would include things like the original purchase price of the product
54
that you're reselling or
55
if you've run a manufacturing business then this would include the cost of your raw materials
56
or the direct labor cost that went into producing your product.
57
As we make more sales we incur more of these direct costs.
58
Cost of goods sold can be a bit of a tricky concept to understand at first.
59
It ties in very closely with inventory in the balance sheet.
60
If you'd like to see me make a video explaining how all of
61
that works then let me know down below in the comments
62
and if you haven't already remember to hit that subscribe button
63
so you don't miss out on all of the other accounting tutorials that we have coming out very soon.
64
Back to the income statement.
65
When we take our revenue and deduct our direct costs of doing business we get to our gross profit.
66
If you're new to accounting then you'll soon discover that we have many different types of profit.
67
Our gross profit is a really useful tool that allows us to measure the efficiency of our production and sales process.
68
I'll show you how that works in a minute.
69
But first let's jump back to indirect costs.
70
These are the costs of running a business
71
which can't directly be traced back to the production of goods or the provision of services.
72
We sometimes call these overheads.
73
Overheads can include fixed costs like rent, employee salaries, insurance costs, admin expenses,
74
legal costs, accounting costs, marketing costs, depreciation and amortization.
75
Whoa, there's a lot of them.
76
Fixed costs like these tend to remain the same.
77
They bear no correlation at all to the sales that your business has made.
78
However, not all overheads are fixed.
79
Variable overheads can loosely correlate with a business's sales, although they can't be directly traced back to the production of goods or the provision of services.
80
These include things like advertising costs, which can indirectly drive sales and sales commissions.
81
Utility costs could also be considered a variable overhead in a manufacturing business because these can increase as we ramp up production.
82
When we deduct our indirect costs of doing business from our gross profit, we come to our operating profit.
83
Operating profit measures the net income that we generated from operations.
84
This is the residual amount that's left over after deducting all of our direct and indirect costs of doing business.
85
So this is our basic income statement.
86
But how does it help us measure a business's financial health?
87
It does that by giving us a means to compare our financial performance against comparative accounting periods.
88
A comparative period is a different period of time.
89
It can be whatever we want it to be.
90
We could compare a current month income statement against last month's income statement or this year versus last year.
91
When we use comparative periods we can calculate the change
92
or movement across each line item down the profit and loss statement
93
and as accountants it's our job to support these movements with a narrative which explains all of the differences.
94
Let's throw in some numbers into an imaginary company and I'll show you what I mean.
95
We'll compare the movements in our P&L year on year.
96
This is going to be for a medium-sized business so we can quote our numbers in thousands of dollars.
97
What have we got here?
98
Our imaginary company has made sales of $110,000 which is up $10,000 from what we made in the prior year.
99
Our cost of goods sold have also increased by $10,000 from $30,000 to $40,000.
100
That's left us with a gross profit of $70,000 which has remained unchanged.
101
Our overheads are fixed at $45,000 which gives us an operating profit of $25,000 in each period.
102
What can we learn from all of this?
103
Well our sales have increased by $10,000 but our gross profit has remained exactly the same.
104
How can that be?
105
A useful metric that we can use to analyze this is gross profit margin.
106
We can calculate our gross profit margin by taking our total product sales
107
and deducting our costs of goods sold and then dividing the whole lot by our product sales.
108
This measures how efficiently we've been producing and selling our imaginary product.
109
In this case our gross profit margin in the current year is around 64%
110
which is actually down from last year's gross profit margin of 70%.
111
How's that possible?
112
Well one of two things could be happening here.
113
Our sales could be shrinking or our costs could be rising.
114
We could be selling more products but at a discount or the cost of our raw materials could be rising.
115
These are the questions that we need to be asking ourselves as accountants, investors or small business owners.
116
We can compare metrics like the gross profit margin across comparative
117
periods to help us identify what questions we should be asking and then Then, that's when the work begins.
118
We need to find out the answers and use them to build a narrative that explains what's going on.
119
Gross profit margin is just one of many business metrics that we can use to analyse the income statement.
120
If you'd like to see me make videos on the others, let me know.
121
Now, this is still quite a basic income statement.
122
In reality there are other indirect costs of doing business which we might need to include as well.
123
Things like interest expenses and tax.
124
These tend to slot in below operating profit because they aren't considered to fall within the normal cost of operations.
125
This is why operating profit is also known as EBIT or earnings before interest and tax.
126
When we deduct our interest
127
and tax from our operating profit we calculate our net profit the bottom line
128
because it's at the bottom of the profit and loss statement.
129
So you can see that there are many different types of profit and loss to consider in accounting.
130
We start off with our revenue and we deduct our direct costs of doing business to come to our gross profit, our top line profit.
131
Below this we take out the indirect costs of running our business to find our operating profit, our EBIT, our earnings before interest and tax.
132
And when we remove interest and tax we calculate our net profit, the bottom line.
133
these different types of profit help us measure performance over a period of time.
134
The main goal of most businesses is to maximize their profits
135
so it's important to be clear on what that means and to be aware of the differences between gross profit,
136
operating profit and net profit which can each tell us a different part of the story.
137
Like I mentioned earlier the income statement is just one of
138
the three main financial statements along with the balance sheet and the cash flow statement.
139
I've made videos covering both of these already which you can find here and here.
140
If you found this one useful give it a like or better yet share it with a friend, why not?
141
Don't forget to subscribe for more accounting tutorials.
142
I'll see you around.

ดาวน์โหลดแอป

ทุกอย่างที่ต้องใช้เพื่อพูดได้คล่อง
AI ให้คะแนนการออกเสียงให้คะแนนทุกประโยค
ฝึก IPAเชี่ยวชาญทุกเสียง
คำศัพท์สร้างคลังคำของคุณ
เกมคำศัพท์เล่นไปเรียนไป

คำศัพท์และข้อสังเกตด้านการพูดสำหรับบทเรียนนี้

บทเรียนฝึกพูดระดับ C1 นี้ใช้วิดีโอ “The INCOME STATEMENT Explained” เป็นสื่อ คำที่ถูกพูดซ้ำบ่อยที่สุด: profit, cost, statement, income, sales วิดีโอนี้มี 142 ประโยค และ 1913 คำ สำหรับฝึกพูดตาม ช่วงที่มีเสียงพูดยาว 11:20 ผู้พูดพูดด้วยความเร็วเป็นธรรมชาติ ประมาณ 169 คำต่อนาที ใกล้เคียงกับบทสนทนาในชีวิตประจำวัน 86% ของคำอยู่ใน 3,000 คำที่ใช้บ่อยที่สุดในภาษาอังกฤษ ส่วนที่เหลือควรดูไว้ก่อนเริ่มฝึก

คำศัพท์สำคัญในวิดีโอนี้

คำที่ยากที่สุด 10 คำในวิดีโอ พร้อมคำอ่านและความหมาย:

คำศัพท์คำอ่านความหมาย
calculate คำกริยา/ˈkælkjʊleɪt/คำนวณ
imaginary คำคุณศัพท์/ɪˈmæd͡ʒɪˌn(ɛ)ɹi/จินตภาพ
metric คำคุณศัพท์/ˈmɛt.ɹɪk/เมตริก
accountant คำนาม/əˈkaʊn.tənt/นักบัญชี
analyze คำกริยา/ˈæn.əˌlaɪz/วิเคราะห์
subtract คำกริยา/səbˈtɹækt/ลบ
correlation คำนาม/ˌkɔɹ.əˈleɪ.ʃən/สหสัมพันธ์
clarity คำนาม/ˈklæɹ.ɪ.ti/ความชัดเจน
investor คำนาม/ɪnˈvɛs.tə(ɹ)/ผู้ลงทุน
wholesale คำนาม/ˈhoʊlseɪl/การขายส่ง, การค้าส่ง

ประโยคที่ควรฝึกพูดซ้ำ

ประโยคสั้น ๆ ที่สมบูรณ์จากวิดีโอ ซึ่งนำไปใช้ในบทสนทนาประจำวันได้:

  • Let's take a closer look at our income statement.
  • I'll show you how that works in a minute.
  • What have we got here?
  • What can we learn from all of this?

ไวยากรณ์ในวิดีโอนี้

โครงสร้างที่ผู้พูดใช้บ่อยที่สุด พร้อมคำพูดจริงจากวิดีโอ:

โครงสร้างในวิดีโอ
ประโยคเงื่อนไข if + อนุประโยค, will/would + กริยา — เงื่อนไขและผลลัพธ์If you're new to accounting then you'll soon
Present perfect have/has + กริยาช่อง 3 — เหตุการณ์ในอดีตที่ยังเกี่ยวข้องกับปัจจุบันI've already made · haven't posted · I've received
Passive voice be + กริยาช่อง 3 — เน้นสิ่งที่เกิดขึ้น ไม่ใช่ผู้กระทำis also known · can be broken · be traced
Relative clauses who / which + อนุประโยค — ข้อมูลเพิ่มเติมเกี่ยวกับคนหรือสิ่งของcosts, which can · profit which can

การออกเสียงที่ควรระวัง

ผู้พูดใช้รูปย่อและรูปลดเสียง 33 ครั้ง เช่น we've, I'll, you're ให้พูดแบบสั้นตามที่ได้ยิน

  • เสียง “sh” และ “zh”: amortization /ˌæmɚtəˈzeɪʃən/, depreciation /dɪˌpɹiːʃɪˈeɪʃən/, snapshot /ˈsnæpʃɒt/, correlation /ˌkɔɹ.əˈleɪ.ʃən/
  • คำยาว — ลงเสียงหนักให้ถูกพยางค์: comparative /kəmˈpæɹətɪv/, imaginary /ɪˈmæd͡ʒɪˌn(ɛ)ɹi/, amortization /ˌæmɚtəˈzeɪʃən/, depreciation /dɪˌpɹiːʃɪˈeɪʃən/, residual /ɹɪˈzɪd͡ʒ.u.əl/

เสียงที่คนไทยมักออกเสียงยาก:

  • เสียงท้ายคำ — ออกเสียงให้ครบ ไม่เปลี่ยนเป็นตัวสะกดแบบไทย: comparative /kəmˈpæɹətɪv/, tutorial /ˌtjuːˈtɔːɹɪəl/, analyze /ˈæn.əˌlaɪz/, resell /ɹiːˈsɛl/, residual /ɹɪˈzɪd͡ʒ.u.əl/
  • /v/ — ไม่ใช่ /w/ ให้ฟันบนแตะริมฝีปากล่าง: overhead /ˈəʊvəˌhɛd/, comparative /kəmˈpæɹətɪv/, descriptive /dəˈskɹɪptɪv/, investor /ɪnˈvɛs.tə(ɹ)/
  • /z/ — เสียงก้อง ไม่ใช่ /s/: analyze /ˈæn.əˌlaɪz/, amortization /ˌæmɚtəˈzeɪʃən/, residual /ɹɪˈzɪd͡ʒ.u.əl/, maximize /ˈmæksəmaɪz/

วิธีฝึกกับวิดีโอนี้

  1. ฟังวิดีโอให้จบหนึ่งรอบโดยยังไม่ต้องพูด แล้วจดคำที่ยังไม่รู้จัก
  2. เริ่มที่ความเร็ว 0.75× พูดตามทีละประโยค แล้วกลับไปใช้ความเร็วปกติเมื่อเริ่มคล่อง
  3. อัดเสียงตัวเองแล้วเทียบกับต้นฉบับ โดยสังเกตคำอย่าง calculate, imaginary, metric เป็นพิเศษ

เทคนิค Shadowing คืออะไร?

Shadowing เป็นเทคนิคการเรียนรู้ภาษาที่ได้รับการรับรองทางวิทยาศาสตร์ พัฒนาขึ้นสำหรับการฝึกนักแปลมืออาชีพ วิธีการนี้เรียบง่ายแต่ทรงพลัง: คุณฟังเสียงภาษาอังกฤษจากเจ้าของภาษาและพูดตามทันที — เหมือนเงาที่ตามผู้พูดด้วยช่วงเวลาห่าง 1-2 วินาที การวิจัยแสดงว่าเทคนิคนี้ปรับปรุงความแม่นยำในการออกเสียง ทำนองเสียง จังหวะ การเชื่อมเสียง การฟังเข้าใจ และความคล่องแคล่วในการพูดได้อย่างมีนัยสำคัญ

เทคนิค shadowing: อ่านคู่มือฉบับเต็มทีละขั้นตอน →