Pratica di Shadowing: The Inflation Problem... It's Worse Than You Think - Impara a parlare inglese con i video
Creazione lezione...
1
Right now, everyone's blaming inflation on the Middle East.
2
That's the narrative we're being told and everyone's accepted it.
3
And it makes sense why.
4
It's easy to follow.
5
There's a clean cause and a clean effect.
6
It's so simple you can draw it on a napkin.
7
Except there's one problem with this story.
8
The Federal Reserve keeps its own inflation scoreboard.
9
They don't use the number you see in the headlines.
10
They target 2% inflation measured by personal consumption expenditures, the PCE.
11
That's the scoreboard that counts.
12
That's also where the mainstream story falls apart.
13
The conflict in the Middle East started in February, just five months ago, but the Federal Reserve's measure has now missed the inflation target for 63 months in a row,
14
more than five years straight.
15
The PCE currently sits at a little over 4%, more than double the Fed's target, and is continuing to climb,
16
so everyone's using a five-month-old story to diagnose a five-year-old problem.
17
And this isn't just a number that only matters to economists.
18
This single number lies at the foundation of every economic decision in the United States, And every rate you pay is priced off what people expect that number to be.
19
Your mortgage, your car loan, what your savings account pays you, what the cash in your wallet is worth next year.
20
So it's worth asking, what's actually going on?
21
Because there's clearly more to the inflation story.
22
Inflation in this country used to move like a pendulum.
23
It would swing up, swing back down, and eventually come to rest around that 2% number.
24
You never questioned it, because you never had to.
25
even had a name for this period of American history, the Great Moderation.
26
From 1985 to 2007, growth was steady, inflation was low, and the whole economy looked like it regulated itself.
27
Except it didn't.
28
There was no invisible hand.
29
There was a real one, someone standing beside the pendulum, giving it a firm push back toward the middle every single time it swung too far,
30
done so reliably for so long that everyone forgot the pendulum was being pushed at all.
31
That's what the last five years are actually about.
32
The thing doing the pushing is now the one in trouble.
33
But before we get there, we need to look closer at that 2% number itself.
34
For a number the entire financial system is anchored to, you'd assume it fell out of some impossibly complex math equation,
35
or it was carved in stone and passed down generations.
36
Well, neither.
37
Somebody chose it.
38
So why the 2%?
39
Here's St. Louis Federal Reserve economist Christopher Neely explaining how they landed on that 2% target number.
40
When central banks were considering what sort of an inflation rate to target,
41
they were really trading off the costs of having inflation with the benefits of having some upward movement in prices,
42
which might have benefits in terms of allowing central banks to stabilize the macroeconomy.
43
So 2% was kind of a happy medium.
44
So while the target number itself may have come from an arbitrary decision, there's still reasoning behind it.
45
But why not go lower?
46
Why not go to zero?
47
That's the obvious question.
48
If inflation's the thing quietly making everything more expensive, why aim for any of it at all?
49
Because while on paper, a zero percent inflation rate sounds great, in reality, it's not.
50
When a recession hits, the Fed's main move is to cut interest rates.
51
In a world with zero inflation, rates already sit near the floor.
52
So the second a real economic downturn arrives, the Fed gets one cut, maybe two, and then slams into zero, structurally trapped and out of road.
53
That's how an ordinary recession can spiral into a decade-long depression.
54
But you can't aim too high either.
55
Push it to 4%, and prices double every 18 years.
56
Businesses can't forecast their cost, and nobody can price a long-term contract without guessing.
57
So 2% is that Goldilocks number, high enough to keep a cushion between the economy and catastrophe, low enough that you barely notice it on an ordinary Tuesday.
58
But actually hitting that number, year after year, is close to impossible.
59
It takes a balancing act so unforgiving, it would make Evel Knievel sweat.
60
And for the last few decades, the Fed made this balancing act look effortless.
61
We're just now finding out how easy it was, now that things have changed.
62
But before I get into that, a quick pause.
63
Because we've been talking about the big picture trends shaping the economy, but let's take a look at something much closer to home.
64
Your cell phone carrier.
65
For most traditional carriers, your data is the real business, and your data usually ends up in one of two places, either packaged up and sold to the highest bidder, or exposed in a data breach.
66
Which brings us to today's sponsor, CAPE.
67
CAPE does the opposite.
68
CAPE is America's privacy-first mobile carrier.
69
You get the same premium, reliable cell service you'd expect from any other carrier, except privacy Security and security are now included.
70
It starts when you sign up.
71
CAPE won't ask for your name, your social security number, or your address.
72
They only collect what's necessary to connect you.
73
Then comes the data your phone creates just by using it, like who you call and text.
74
While traditional carriers hoard this data for years, CAPE deletes that information after just 24 hours.
75
But that's not all.
76
There's also your phone number.
77
It's one of the most sensitive pieces of information about you, yet you're constantly forced to hand it out.
78
With CAPE's new secondary numbers feature, you get two additional encrypted phone numbers included in your plan, perfect for sign-ups, online shopping, and account verification.
79
CAPE lets you stay connected without having to compromise your privacy.
80
If you're interested in checking out CAPE, you can get 33% off your first six months using the link below.
81
Promo code CASUAL33.
82
Thank you to CAPE for sponsoring this video.
83
Now back to the Federal Reserve's World Class Balancing Act.
84
For the last few decades, we managed to control inflation.
85
The walk towards the 2% target looked effortless.
86
But it only looked effortless because the tightrope was 6 inches off the ground.
87
And the only reason we know that is because we've seen what the same walk looks like 60 feet up.
88
But I'm trying to be a more positive guy these days.
89
So before I show you the ugly, let me show you the good part.
90
Back when the Feds still had room to work with.
91
Let's rewind to the late 70s.
92
Inflation wasn't drifting anymore.
93
It was sprinting.
94
It peaked at over 13.5%.
95
At that pace, prices double in about nine years.
96
The dollar in your pocket was rotting while you held it, and every single person could feel it happening.
97
So who do you call when inflation is out of control?
98
No. Not Ghostbusters.
99
You call 6'7", cigar-smoking Paul Volcker, the kind of man who looks like he eats recessions for breakfast.
100
Volcker takes over as Fed chair in 1979 and does the one thing nobody else had the stomach for.
101
He drives interest rates to 20%.
102
He deliberately triggers not one recession, but two, back to back, strangling the money supply until inflation has nothing left to feed on.
103
It was so aggressive, it earned a name of its own, the Volcker Shock.
104
And it worked.
105
Inflation went from over 13.5% down to bottoming out under 2% in the late 80s.
106
So take a look at the timeline.
107
From 1980 to 1983, Volcker tightens monetary policy aggressively, triggers two back to back recessions and successfully drops inflation by more than 10 points.
108
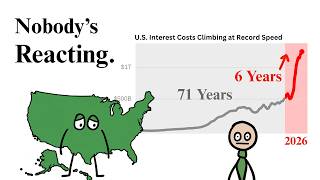
Two years later, the United States enters the Great Moderation Era, a 23-year-long period defined by steady growth and historically low economic volatility.
109
Which raises the obvious question, the one probably forming in your head right now, if it worked for Volcker, why can't the Fed just run the same playbook again today?
110
It's because he had one advantage nobody talks about, the country could absorb the damage.
111
When Volcker first claimed the throne, the national debt was about a quarter the size of the economy.
112
By today's standards, pretty much nothing.
113
So when he drove rates to 20%, it was brutal, but it was clean.
114
Raising rates did the one thing he intended it to do, slam the brakes.
115
But that world is gone.
116
The national debt is now sitting around 100% of GDP, a one-to-one match with the entire economy.
117
The last time it was this high was the Second World War, but the number is only half of it.
118
The other half is what the number does.
119
When the Fed raises rates now, it presses down in two places at once.
120
The first is the breaks.
121
Higher rates, pricier loans, less borrowing and a slower economy.
122
Simple.
123
The second is hidden underneath and quietly emerges by accident.
124
Higher rates also mean the government pays more interest on what it already owes.
125
And that bill is not small.
126
Net interest is running around a trillion dollars a year, more than the entire military budget.
127
In 2021, interest ate about 9% of every dollar the federal government collected.
128
This year, it's 19%.
129
But those interest payments don't just vanish from the economy.
130
It lands in the hands of the pension funds, banks, foreign governments, and other investors who lent the US government money in the first place.
131
So every time the Fed raises rates to cool the economy down, it also raises the size of the check that gets written and paid out, which then gets spent, lended out,
132
or rolled into the next bond at the new higher rate.
133
Which basically means the same move that's supposed to pull money out of the economy starts quietly sending it back in.
134
So one foot presses the brake, the other one quietly presses the gas.
135
And the heavier the debt, the harder that second foot pushes.
136
At 25% of GDP, you barely feel it.
137
At 100%, both pedals are floored and the brake is wired to the accelerator.
138
Two economists saw this danger coming in 1981.
139
Thomas Sargent and Neil Wallace predicted it in one of the most influential macroeconomic papers of the last 50 years.
140
While the title doesn't exactly scream page turner, and it's not exactly the easiest read.
141
In fact, I'd probably rather watch paint dry than read through it a second time.
142
The stuff inside it is very interesting.
143
They warn that if the government never runs a surplus, the central bank can't make the debt smaller.
144
All it gets to decide is what form the debt takes, bonds or cash.
145
Those are the two options.
146
So when the Fed fights inflation, it's squeezing the cash side, which means the bond side has to grow to make up the difference.
147
And bonds pay interest.
148
So the longer the Fed holds the line, the faster that pile of debt compounds.
149
So the tightening that brings inflation down today is the same thing that forces somebody to print later.
150
Meaning the Fed isn't actually addressing the root of the problem.
151
They're not actually fighting the inflation, they're just postponing it.
152
And if you think this is just some doomer theory from 1981 with no bearing on today, well guess what?
153
A few weeks ago the new Fed chair Kevin Warsh launched five new task forces to tackle different economic problems.
154
One of them is an inflation frameworks task force to reassess how the Fed measures, understands, and responds to structural drivers of inflation.
155
Three people were picked to lead this team.
156
One of them is Thomas Sargent.
157
The man who co-wrote the paper from 45 years ago is
158
now being asked by the Fed to lead a team tackling the inflation issues.
159
So inflation is clearly a concern for the Federal Reserve.
160
But when you step outside and look around, it's quiet.
161
Gas got cheaper last month.
162
The headlines said cooling, you might even think this whole thing already sorted itself out.
163
But the thing people forget is the ground is always the last thing to shake.
164
By the time you feel an earthquake under your feet, the fault lines slipped a while ago and the impact's already on its way to you.
165
The inflation numbers you see in the headlines are that ground.
166
They move last.
167
Housing is the clearest example.
168
It's more than 35% of the entire basket the headline number is built on, and it's the slowest moving piece in it, because rents lock in for a year and reset in steps.
169
So a big chunk of today's reading is measuring pressure that was released months ago.
170
When the headlines say everything's calm, it's telling you the ground held.
171
Yesterday.
172
Waiting on the inflation number means finding out last.
173
You need to work backwards to get to the truth.
174
When you strip everything away, inflation is one thing, price is going up.
175
But a price only goes up if somebody actually pays the higher one.
176
And nobody pays more without having more to pay with.
177
So the money moves first.
178
Every time.
179
And there's a number that measures exactly that.
180
It's called M2.
181
It's one of the main ways economists measure how much money is sloshing around the system.
182
Think of it as all the cash within arm's reach of the economy.
183
After 2020, the line goes pretty much vertical.
184
The M2 money supply is currently growing at over 5.5% a year, the fastest pace since July 2022.
185
But money doesn't reappear on its own, somebody has to put it there.
186
So if inflation's the enemy, who exactly is quietly pumping fresh dollars back into the system?
187
The answer's the Federal Reserve.
188
To see how, you need to understand the least understood tool the Fed owns.
189
Forget interest rates for a second.
190
There's a second lever.
191
This one's hidden in the back of Jerome Powell's closet, and it only comes out in case of an emergency.
192
It's a literal money printer.
193
When the economy's dying, like in 2020, the Fed creates money out of thin air and uses it to buy bonds, pushing that new money into the system to keep it alive.
194
That flood of new money is called quantitative easing, and in the pandemic, they ran it harder than at any point in history.
195
The Fed's balance sheet went from around $4 trillion to nearly $9 trillion in about two years, leading to inflation spiking to over 9% in June 2022.
196
But when inflation caught fire, the Fed was forced to do something they've only done twice in its more than 100-year history.
197
They ran the money printer in reverse.
198
Instead of creating money to buy bonds, the Fed let the bonds it already held expire and didn't replace them.
199
Every month, a little less money in the system than the month before.
200
This policy is called quantitative tightening, and it started in June of 2022.
201
Over the next three and a half years, the Fed took more than $2.2 trillion off its balance sheet.
202
It worked well enough that the money supply itself contracted, which sounds minor, but it's not.
203
The last time the amount of money in the American economy meaningfully shrank was the Great Depression.
204
But you also can't tighten forever.
205
The United States financial system needs a certain amount of cash just sitting in it to function day to day, and if you drain past that line, things start breaking.
206
So on December 1st of last year, the Fed announced quantitative tightening was over.
207
They'd successfully taken out about half of the more than $5 trillion that was injected in the financial system during the pandemic.
208
But then Jerome Powell snuck back out of the closet and turned the engine back on.
209
Eleven days later, on December 12th, the Fed started buying bonds again, around $40 billion a month.
210
The balance sheet it spent three and a half years draining is now refilling.
211
So all this leaves us with a country running two very different stories at the same time.
212
The first one shows up in the monthly reports, the headline numbers.
213
That's the story everybody argues about, and you get a new story every 30 days.
214
The second runs underneath all of it, the structural stuff.
215
The Congressional Budget Office now estimates the deficit for this fiscal year will reach $1.4 trillion.
216
That's 5.8% of the entire economy and far above the previous 50-year average of 3.8%.
217
The total national debt is closing in on $40 trillion, and the interest we pay on that debt is now over a trillion dollars a year.
218
In 2021, interest ate about 9 cents out of every dollar the federal government collected.
219
This year it's 19.
220
It more than doubled in five years.
221
Interest is now the third largest line in the entire federal budget.
222
We spend more on it than we spend on the entire military.
223
The debt snowball is playing out exactly as Thomas Sargent and Neil Wallace warned.
224
So how do we actually fix this mess?
225
The best answer I've seen comes from the golden boy of the finance world, Warren Buffett.
226
He was asked how he would deal with the deficit.
227
Here's what he said.
228
I get in the deficit in five minutes.
229
How?
230
You just pass a law that says that anytime there's a deficit of more than 3% of GDP, all sitting members of Congress are ineligible for re-election.
231
Now you've got the incentives in the right place, right?
232
So it's capable of being done.
233
A law that bars every sitting member of Congress from re-election anytime the deficit runs past 3% of GDP.
234
He was laughing when he said it, but he's also completely right.
235
We have an incentives problem.
236
It's not just a problem on the left, or just a problem on the right.
237
It's an American problem.
238
Both parties do it.
239
Think about how somebody actually gets a job in Congress.
240
They campaign on promises, telling you they'll do this and that, because that's what wins.
241
Nobody builds a career in Congress promising people less, so the incentives only point one direction, spending more.
242
Which is how the national deficit has run past 3% of GDP for pretty much the entire 21st century.
243
It hasn't just been an expensive couple of years, it's structural spending.
244
We've been spending more than we bring in for a quarter of a century straight.
245
The problem with going down this path is, it compounds.
246
The more we borrow, the more interest we owe.
247
The more interest we owe, the more we have to borrow.
248
It's a never-ending, repeating cycle.
249
We're on an unsustainable path that will eventually have to come to an end.
250
And every year we put this off, the bill to deal with it just gets bigger.
251
I'm curious to hear where other people land on this.
252
Is this something we need to deal with now, or are people crashing out over nothing?
253
Drop a comment and let me know.
254
I'll be reading through them.
255
Maybe Buffett's plan is too extreme.
256
Or maybe it isn't extreme enough.
257
We can argue about the right solution all day, but what we can't argue about is that this doesn't fix itself.
258
Something eventually has to change.

Vocabolario e note di pronuncia per questa lezione

Questa lezione di conversazione di livello B2 si basa sul video “The Inflation Problem... It's Worse Than You Think”. Le parole che ritornano più spesso: inflation, Fed, rate, interest. Questo video contiene 258 frasi e 3195 parole da ripetere con lo shadowing. Il parlato dura 16:44. Chi parla va veloce, circa 191 parole al minuto: aspettati suoni legati e ridotti. Il 84% delle parole rientra nelle 3.000 più comuni dell’inglese; conviene studiare le altre prima di iniziare.

Vocaboli chiave di questo video

Le 15 parole più avanzate del video, con pronuncia e significato:

ParolaPronunciaSignificato
inflation sostantivo/ɪnˈfleɪ.ʃən/inflazione
headline sostantivo/ˈhɛd.laɪn/titolo
deficit sostantivo/ˈdɛfəsɪt/deficit, disavanzo
recession sostantivo/ɹɪˈsɛʃn̩/recessione
tighten verbo/ˈtaɪ.tən/stringere
economist sostantivo/iˈkɑ.nə.mɪst/economista
effortless aggettivo/ˈɛfə(ɹ)tlɪs/senza sforzo
pendulum sostantivo/ˈpɛnd͡ʒələm/pendolo
quantitative aggettivo/ˈkwɑn.təˌteɪ.tɪv/quantitativo
incentive sostantivo/ɪnˈsɛntɪv/incentivo
structural aggettivo/ˈstɹʌk(t͡)ʃəɹəl/strutturale
printer sostantivo/ˈpɹɪntɚ/stampante
borrow verbo/ˈbɑɹ.oʊ/prendere in prestito
warn verbo/woɹn/avvertire, avvisare
drain sostantivo/dɹiːn/scolo

I phrasal verb che sentirai

ParolaPronunciaSignificato
find out verboscoprire
go up verbosalire
back down verbocedere
check out verboinvestigare
fall apart verbocadere a pezzi
get off verboscendere
make up verbo/ˌmeɪk ˈʌp/comporsi
pass down verbopassare

Frasi da ripetere

Frasi brevi e complete del video che puoi riutilizzare nella conversazione di tutti i giorni:

  • They only collect what's necessary to connect you.
  • There's also your phone number.
  • I'll be reading through them.

La grammatica di questo video

Le strutture che chi parla usa di più, con le parole esatte del video:

StrutturaNel video
Present perfect continuous have/has been + -ing — un’azione iniziata prima e ancora in corsowe've been talking · We've been spending
Forma passiva be + participio passato — conta ciò che accade, non chi lo fabeing told · is priced · being pushed
Present perfect have/has + participio passato — un’azione passata che conta ancora adessohas now missed · have changed · we've seen
Frasi relative who / which + frase — un’informazione in più su una persona o una cosaman who looks · side, which means · man who co

Pronuncia a cui fare attenzione

Chi parla usa 40 contrazioni e forme ridotte, come can't, doesn't, isn't. Pronunciale nella forma breve, così come le senti.

  • I suoni “th”: underneath /ˌʌndɚˈniθ/, throne /θɹəʊ̯n/, mathematics /mæθ(.ə)ˈmæt.ɪks/, earthquake /ˈɝθkweɪk/
  • I suoni “sh” e “zh”: inflation /ɪnˈfleɪ.ʃən/, recession /ɹɪˈsɛʃn̩/, structural /ˈstɹʌk(t͡)ʃəɹəl/, cushion /ˈkʊʃən/, verification /ˌvɛ.ɹə.fɪˈkeɪ.ʃən/
  • Parole lunghe — attenzione all’accento: economist /iˈkɑ.nə.mɪst/, quantitative /ˈkwɑn.təˌteɪ.tɪv/, accelerator /əkˈsɛl.əˌɹeɪ.tɚ/, catastrophe /kəˈtæstɹəfi/, verification /ˌvɛ.ɹə.fɪˈkeɪ.ʃən/

I suoni difficili per chi parla italiano:

  • /h/ — va soffiata, non è muta: headline /ˈhɛd.laɪn/, historically /hɪˈstɔɹɪkli/
  • Consonante finale — senza aggiungere una vocale dopo: deficit /ˈdɛfəsɪt/, economist /iˈkɑ.nə.mɪst/, effortless /ˈɛfə(ɹ)tlɪs/, quantitative /ˈkwɑn.təˌteɪ.tɪv/, incentive /ɪnˈsɛntɪv/
  • /æ/ — più aperta della “e”: slam /ˈslæm/, catastrophe /kəˈtæstɹəfi/, backward /ˈbækwɚd/, absorb /æbˈsɔɹb/, anchor /ˈæŋ.kəː/

Come esercitarsi con questo video

  1. Ascolta tutto il video una volta senza parlare e annota le parole che non conosci.
  2. Inizia a velocità 0,75×, fai shadowing frase per frase e torna alla velocità normale quando diventa facile.
  3. Registrati e confronta con l’originale, facendo attenzione a parole come inflation, headline, deficit.

Cos'è la tecnica dello Shadowing?

Shadowing è una tecnica di apprendimento delle lingue supportata da studi scientifici, originariamente sviluppata per la formazione dei traduttori professionisti e resa popolare dal poliglotta Dr. Alexander Arguelles. Il metodo è semplice ma potente: ascolti un audio in inglese di madrelingua e lo ripeti immediatamente ad alta voce — come un'ombra che segue il parlante con un ritardo di solo 1–2 secondi. A differenza dell'ascolto passivo o degli esercizi di grammatica, lo shadowing costringe il tuo cervello e i muscoli della bocca a elaborare e riprodurre simultaneamente i modelli di discorso reale. La ricerca dimostra che migliora significativamente la precisione della pronuncia, l'intonazione, il ritmo, il discorso connesso, la comprensione dell'ascolto e la fluidità del parlato — rendendolo uno dei metodi più efficaci per la preparazione alla prova di speaking dell'IELTS e per la comunicazione reale in inglese.

Tecnica dello shadowing: leggi la guida completa passo dopo passo →