Shadowing Practice: Fed in July: A Weaker Case for Hiking - Learn English Speaking with Video

בחר מצב תרגול

כל מצב פותח חדר תרגול במסך מלא.

122 משפטים
אם המשפטים קצרים או ארוכים מדי, לחץ על ערוך כדי להתאים אותם.
1
Welcome to Thoughts on the Market.
2
I'm Matthew Hornbach, Global Head of MacroStrategy.
3
And I'm Michael Gapin, Morgan Stanley's Chief U.S.
4
Economist.
5
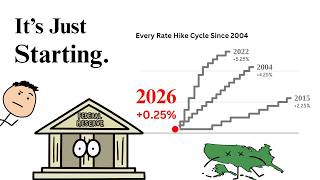
Today, will the Fed hold or hike?
6
It's the question in the market right now.
7
It's Tuesday, July 28th at 9.30 a.m in New York.
8
Will the Fed display patience or has it run out of patience?
9
That's the question hanging over the July FOMC meeting currently underway.
10
We believe the former.
11
We expect the Fed to keep the target range for the federal funds rate unchanged at 3.5% to 3.75%.
12
The statement will probably also remain unchanged, reiterating the ample reserve policy,
13
economic activity expanding at a solid pace despite elevated uncertainty.
14
So, Mike, what's your assessment of the situation beyond that?
15
Our assessment of the July FOMC meeting is actually the case
16
for hikes is not as persuasive now as it was in June.
17
And I think when we say that and when we come to the decision the Fed will stay on hold this week,
18
we're basing it mainly on the data that has come in since the June FOMC meeting.
19
And two important pieces on that front are employment growth moderated.
20
So in the June meeting, the three-month average payroll gain was running at about $188,000 per month,
21
and I think it gave the sense that the labor market was really accelerating
22
and there was downside risk to the unemployment rate.
23
The subsequent employment data changed that view.
24
Now it looks like there is much less of an acceleration in hiring and momentum has slowed.
25
So the labor market doesn't look quite as robust.
26
Second, there was a lot of information, we think, a lot of signal, about disinflation.
27
So yes, recent volatility in the Middle East did push oil prices temporarily higher.
28
We'll see where that goes.
29
But underneath the hood, there was significant softness in goods inflation and services inflation, particularly related to housing.
30
So we do think that there was a lot of evidence that disinflation is here.
31
So with those two things in mind, we think there's less of a case to hike in July than there was in June.
32
So we think the right thing, or what we think the Fed will do, is to skip July, try and buy a little more time, get a little more information.
33
If disinflation is indeed here, the Fed stays on hold.
34
If not, and inflation stays firm, well, they could move to rate hikes later this year.
35
But we think the case to hike in July is less compelling than it was in June.
36
Well, they certainly will get a lot more information between the July meeting
37
and the September meeting if memory serves at least two more rounds of all of the major economic data points,
38
payrolls, CPI, and so on.
39
That's right.
40
The gap between the The July FOMC meeting and the September FOMC meeting is the longest on the Fed's calendar.
41
Of course, in part, that makes room for Jackson Hole in August, which if the Fed were moving to a tightening cycle, could be a venue to lay out the case for that.
42
But you're right, they will see multiple employment and inflation reports before they meet again in September.
43
If they really wanted to get ahead of that data and move at this meeting,
44
what is the case for hiking rates in July?
45
How would you think about that perspective?
46
I think you could make a couple of cases to hike now.
47
One is recent volatility
48
and conflict in the Middle East has pushed oil prices higher
49
maybe it convinces you you're in a prolonged oil risk premium scenario and inflation will not dissipate.
50
Second, I think you could argue, well, it's a balance of risks argument, and we think risks have just shifted in the direction of inflation,
51
where last year they were in the direction of a weaker labor market.
52
We eased last year, let's just reverse those risk management rate cuts this year.
53
So it's not about inflation in hand.
54
It's about your view of risks around inflation.
55
Another, I think, and to me this is the most important one, is maybe Walsh wants a regime change in the reaction function.
56
In other words, he emphasizes price stability and achieving the 2% target.
57
Well, at some point, words are words and actions are actions, and maybe what he desires is a more hawkish reaction function
58
and kind of a higher interest rate all else equal to guide inflation down to 2% more quickly.
59
So I think, Matt, if we're wrong this week, I think the main reason we're wrong is I'm thinking under an older reaction function,
60
and Warsh is bringing a new one.
61
And right now, we don't exactly know what his reaction function is, and he could reveal it this week as being in a
62
direction where he really wants to concentrate on the inflation side of the mandate to the exclusion of nearly everything else.
63
Well, I don't think that's lost on markets at all.
64
In fact, I think
65
that the rise in yields we've seen in the bond market
66
concentrated in the real yield component of the 10-year Treasury bond
67
tells you a lot about how investors are thinking the Fed
68
will react to higher energy prices as energy prices have gone up,
69
so have bond yields, the relationship between those two asset prices are very strong.
70
And usually what that suggests is
71
if the real yield is going up more than the break-even inflation rate is going up as energy prices rise,
72
it's telling you that investors think the Fed will not look through the rise in energy prices.
73
If you have the opposite happen, where your break-even inflation rate is going higher, more so than the real interest rate is going higher,
74
that would suggest investors think the Fed will look through the energy price increase.
75
That just hasn't been the case.
76
And so I think investors are very much attuned to what they think is the right reaction function for the Fed.
77
But I guess we'll see.
78
Only time will tell.
79
And I think in order to help us tell what the right reaction function is,
80
we'll need some communication from the Fed and maybe that's where I want to go next with you, is on communication.
81
It does seem like there have been fewer FOMC participants speaking to the public since Chairman Warsh began his tenure as chairman. Is that your impression?
82
How do you think about communication?
83
And since we are in the midst of this FOMC meeting, the press conference, what do you think about press conferences going forward?
84
I do think you're right.
85
I haven't counted up the literal official FOMC communications.
86
I do think there have likely been fewer speeches and or interviews given recently.
87
And whether or not that's a function of Kevin Warsh is the chairman or it's summer and things move a little slower, I don't know.
88
I will say though that when participants have spoken, I think we're getting the same, say, normal communication that they brought in the past.
89
So far, I don't read participants as unwilling to provide their view about the outlook for the economy and for monetary policy.
90
On the press conference, boy, would that be a change.
91
I've been of the view
92
that you probably will not get what I'll call a major change to the SEPs
93
or the press conferences in terms of their frequency until the task force on communications has run its course,
94
where I think the deadline is ultimately later this year.
95
So I don't think the schedule of press conferences will change until 2027, if it changes at all.
96
But if we don't have them, the way that I would look at that, Matt, is to say, if the Fed's speaking less,
97
there will be a vacuum out there to some degree.
98
So if the Fed's giving its view on the outlook and monetary policy less frequently, something else will fill that narrative.
99
Whether it's markets or the private sector or whatever it is, vacuums are going to get filled.
100
If the Fed's speaking less, somebody else will speak more.
101
Maybe that drives volatility more.
102
I guess it would depend on the situation.
103
But I think polling press conferences would be a major surprise.
104
I don't think it's in market expectations, and my belief is it would probably lead to some increase in volatility over time.
105
How would you read it?
106
Absolutely.
107
I think the void has already begun to be filled by investors and how they think about the Fed's reaction function,
108
rightly or wrongly, which is why I think we've seen real yields move in a very positively correlated way with energy prices.
109
investors are intuiting a certain reaction function to higher energy prices.
110
Whether or not that is the correct view, only time will tell.
111
And if we do have a press conference at this upcoming meeting, which it looks very likely that we will,
112
investors are going to, as they have done now for, really since the press conferences began,
113
they're going to pay attention to every nuance, every shift in tonality of the chairman's voice,
114
how he chooses to address certain questions versus others,
115
or whether he chooses to address questions will certainly be important for market participants
116
and how they invest in the bond and the currency markets.
117
Well, with that, Mike, thanks again for taking the time to talk.
118
I look forward to catching up with you again in late August around the Jackson Hole Symposium.
119
Great speaking with you, Matt.
120
Thanks for having me on.
121
And thanks for listening.
122
If you enjoy Thoughts on the Market, please leave us a review wherever you listen and share the podcast with a friend or colleague today.

הורד אפליקציה

כל מה שאתה צריך כדי לדבר בשטף

הגיית AIציון לכל משפט
תרגול IPAשלוט בכל צליל
אוצר מיליםבנה את מאגר המילים שלך
משחק אוצר מיליםלמד תוך כדי משחק

אותו ערוץ

FOR YOU

המלץ על סרטון

אוצר מילים והערות הגייה לשיעור הזה

שיעור הדיבור הזה ברמה C1 מבוסס על הסרטון “Fed in July: A Weaker Case for Hiking”. המילים שחוזרות הכי הרבה: inflation, Fed, meeting, price, function. בסרטון הזה יש 122 משפטים ו-1643 מילים לתרגול Shadowing. הדיבור נמשך 10:31. הדובר מדבר בקצב טבעי של כ-156 מילים בדקה, קרוב לשיחה יומיומית. 84% מהמילים נמצאות בין 3,000 המילים הנפוצות ביותר באנגלית; כדאי ללמוד את השאר לפני שמתחילים.

אוצר מילים מרכזי בסרטון הזה

13 המילים המתקדמות ביותר בסרטון, עם ההגייה והמשמעות שלהן:

מילההגייהמשמעות
investor שם עצם/ɪnˈvɛs.tə(ɹ)/מַשְׁקִיעַ
participant שם עצם/pɑːɹˈtɪsəpənt/מִשׁתַתֵף
vacuum שם עצם/ˈvæ.kjuːm/ואקום, ריק
hawkish שם תואר/ˈhɔːkɪʃ/ניצי
accelerate פועל/ɪkˈsɛl.əˌɹeɪt/האיץ
exclusion שם עצם/ɪksˈkluːʒən/הדרה
acceleration שם עצם/əkˌsɛl.əˈɹeɪ.ʃən/האצה
literal שם תואר/ˈlɪt(ə)ɹəl/מילולי
tenure שם עצם/ˈtɛn.jʊə/קביעות
robust שם תואר/ɹəʊˈbʌst/חָסוֹן, אֵיתָן
mandate שם עצם/ˈmændeɪ̯t/סַמְכוּת, מַנְדָּט
colleague שם עצם/ˈkɒliːɡ/עָמִית, עמיתה
momentum שם עצם/ˌmə(ʊ)ˈmɛntəm/תֶּנַע

Phrasal verbs שתשמעו

מילהמשמעות
go up פועלעָלָה

משפטים שכדאי לחזור עליהם

משפטים קצרים ושלמים מהסרטון שאפשר להשתמש בהם בשיחה יומיומית:

  • We'll see where that goes.
  • How would you think about that perspective?
  • It's about your view of risks around inflation.
  • How do you think about communication?
  • How would you read it?

הגייה ששווה לשים לב אליה

הדובר משתמש ב-28 קיצורים וצורות מקוצרות, כמו don't, we're, I'm. אמרו אותם בצורה הקצרה, כפי שאתם שומעים אותם.

  • הצלילים של “sh” ו-“zh”: disinflation /ˈdɪsɪnfleɪ̯ʃən/, hawkish /ˈhɔːkɪʃ/, exclusion /ɪksˈkluːʒən/, acceleration /əkˌsɛl.əˈɹeɪ.ʃən/, expectation /ˌɛk.spɛkˈteɪ.ʃən/
  • מילים ארוכות — שימו לב להטעמה: volatility /ˌvɑ.ləˈtɪl.ə.ti/, participant /pɑːɹˈtɪsəpənt/, disinflation /ˈdɪsɪnfleɪ̯ʃən/, reiterate /ɹiːˈɪt.ə.ɹeɪt/, tonality /toʊnˈæl.ɪ.ti/

צלילים שדוברי עברית מתקשים בהם:

  • /w/ — שפתיים מעוגלות, לא /v/: persuasive /pə(ɹ)ˈsweɪsɪv/, unwilling /ʌnˈwɪlɪŋ/, underway /ʌndəɹˈweɪ/, weaker /ˈwikɚ/
  • /æ/ — פתוח יותר מה-“אֶ” העברית, לא כמו “a” ב-“cup”: vacuum /ˈvæ.kjuːm/, tonality /toʊnˈæl.ɪ.ti/, ample /ˈæm.pəl/, mandate /ˈmændeɪ̯t/
  • /r/ — הלשון לא נוגעת בשום מקום, לא ה-“ר” הגרונית: investor /ɪnˈvɛs.tə(ɹ)/, participant /pɑːɹˈtɪsəpənt/, payroll /ˈpeɪˌɹəʊl/, concentrate /ˈkɑn.sən.tɹeɪt/, correlate /ˈkɔɹəleɪt/

איך לתרגל עם הסרטון הזה

  1. הקשיבו לכל הסרטון פעם אחת בלי לדבר, ורשמו את המילים שאתם לא מכירים.
  2. התחילו במהירות 0.75×, תרגלו Shadowing משפט אחר משפט, וחזרו למהירות רגילה כשזה מרגיש קל.
  3. הקליטו את עצמכם והשוו למקור, תוך תשומת לב למילים כמו investor, participant, vacuum.

מהי טכניקת השאדואינג?

שאדואינג היא טכניקת למידת שפה מבוססת מדע שפותחה במקור להכשרת מתורגמנים מקצועיים ופופולרית על ידי הפוליגלוט ד"ר אלכסנדר ארגואלס. השיטה פשוטה אך עוצמתית: אתה מקשיב לאודיו באנגלית ילידית וחוזר עליו בקול רם מיד — כמו צל העוקב אחרי הדובר עם עיכוב של 1–2 שניות בלבד. בניגוד להאזנה פסיבית או תרגילי דקדוק, שאדואינג מכריח את המוח והשרירים בפה לעבד ולשחזר דפוסי דיבור אמיתיים בו זמנית. מחקרים מראים שזה משפר משמעותית את דיוק ההגייה, האינטונציה, הקצב, הדיבור המחובר, הבנת השמיעה ושטף הדיבור — מה שהופך אותו לאחת השיטות היעילות ביותר להכנה לIELTS Speaking ולתקשורת באנגלית בעולם האמיתי.

טכניקת Shadowing: קרא את המדריך המלא שלב אחר שלב →